
Green Tiger Markets PH Electricity September Update
Dear Green Tiger Market Client,
Market cycles are an undeniable force in commodities markets, swinging between periods of scarcity and surplus. What begins as a “tight” market—where demand overwhelms limited supply—inevitably gives way to times of abundance, tipping conditions toward oversupply and weaker relative demand. These cycles typically span several years, sometimes presenting misleading signals along the way, but the broader trend always reasserts itself. Right now, it’s clear: the Philippines electricity market has transitioned from tightness to newfound looseness.
The turbulence we’ve seen in the spot market recently serves as a powerful reminder: hedging your positions isn’t just smart—it’s essential. Even with a dramatic price surge at the start of the month, Luzon’s August Baseload managed to stay under 4P/Kwh on average. Meanwhile, Visayas and Mindanao consumers faced a tougher reality, with spot Baseload averages climbing above 6P/Kwh.
For generators that stayed online through the recent outages, imagine where prices might have landed had there been no interruptions at all. Early September is already setting the stage for significantly lower prices compared to both this past summer and last year. So, what’s the bottom line here?
For consumers, there’s never been a better time to secure your energy costs on GTM. With today’s market, you can lock in select months below 4P/Kwh—and secure the entire year at rates in the low 4s. Don’t miss this window—act now.
For generators, if 2025 hasn’t delivered the results you hoped for, ask yourself—do you want to chance another year of uncertainty? Right now, you have the opportunity to secure substantial volumes at prices higher than this year’s average, giving you peace of mind and protecting your margins. While this year’s bids may not match last year’s, is it worth risking even lower prices? Imagine if Baseload averages drop to 3P/Kwh next year—now is the time to lock in your advantage.
For unhedged solar developers, the story this year is clear: average prices have dipped to 3.3P/Kwh and continue to trend even lower against baseload. There are still compelling opportunities to lock in favorable hedges—act quickly, because these windows don’t stay open for long.
For bulk consumers with WESM-indexed contracts, now is your moment to lock in costs on GTM at rates dramatically lower than anything seen from 2022 to 2024—all with just a few clicks.
Through August, Luzon Baseload averaged just under 4P/Kwh for the Load Weighted Average Price, a sharp drop from the approximately 5.85P/Kwh seen in the first eight months of last year. That’s nearly a 30% year-on-year decline. While there are many factors at play, the question now becomes: what could spark tighter market conditions next year compared to this year?
With so many moving parts influencing electricity prices, staying unhedged leaves your company and your shareholders exposed to significant financial risk. If your business faces large WESM exposure, now is the perfect time to take a measured approach: start with a pilot, committing 10–15% of your unhedged portfolio into the forward market each month or quarter over the next 12–24 months. Every matched order will bolster your financial security—and getting active, even with a small percentage, helps your team build the internal capabilities to confidently expand your hedges in the future.
Many leading Philippine energy companies already hedge currencies, interest rates, and fuel. With the GTM market now available, it’s time to add electricity price risk management to your toolkit.
As a final note, we’re excited to announce that Green Tiger Markets is partnering with the Energy Lawyers Association of the Philippines (ELAP) to host a complimentary introductory session on financial derivatives for Philippine energy lawyers. Join us September 17 at PSE BGC for this special event. If you’d like your legal team to attend, simply reach out to us or ELAP for further details.
Interested in learning more about how to improve supply/demand balance forecasting?
Areas of Focus for Hedging in May
Buyers turning to sellers
Lower prices for the balance of the year and next year
Sellers are sniffing around in 2026, and now 2027
Bids for 2025 have evaporated given the lower spot prices. Current marks have Q425 at 3P/Kwh and Q126 just a hair over Q4
Cal 26 4200 Bid @ 4500 Offered
Cal 27 4100 Bid @ 4800 Offered
Long term midday (5 years or more) offered at 4300.
While bids have been backing up in generally, we are witnessing a strong increase in activity from a variety of participants looking to lock in prices for next year. We have registered a handful of new clients in the last two months, and they are becoming more active.
Live pricing levels
Given the fast-paced shifts in market pricing, we encourage you to reach out directly for the latest and most detailed list of active orders. Connect with us to stay ahead and access the most current opportunities—thank you!
Meet with a GTM Risk Management Specialist
In a quick phone call we can help stabilize your future.
Market Data and Commentary
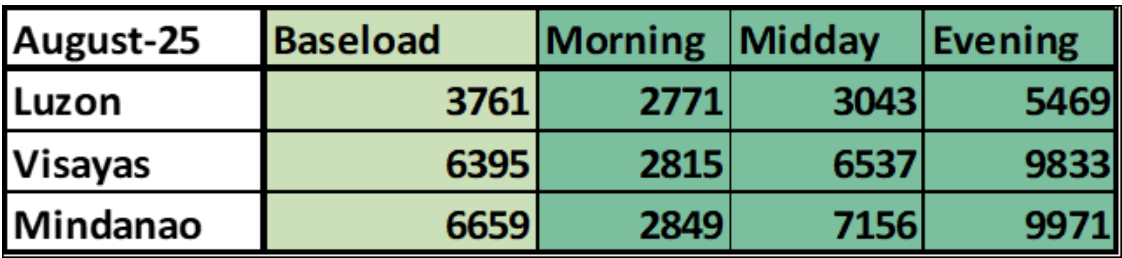
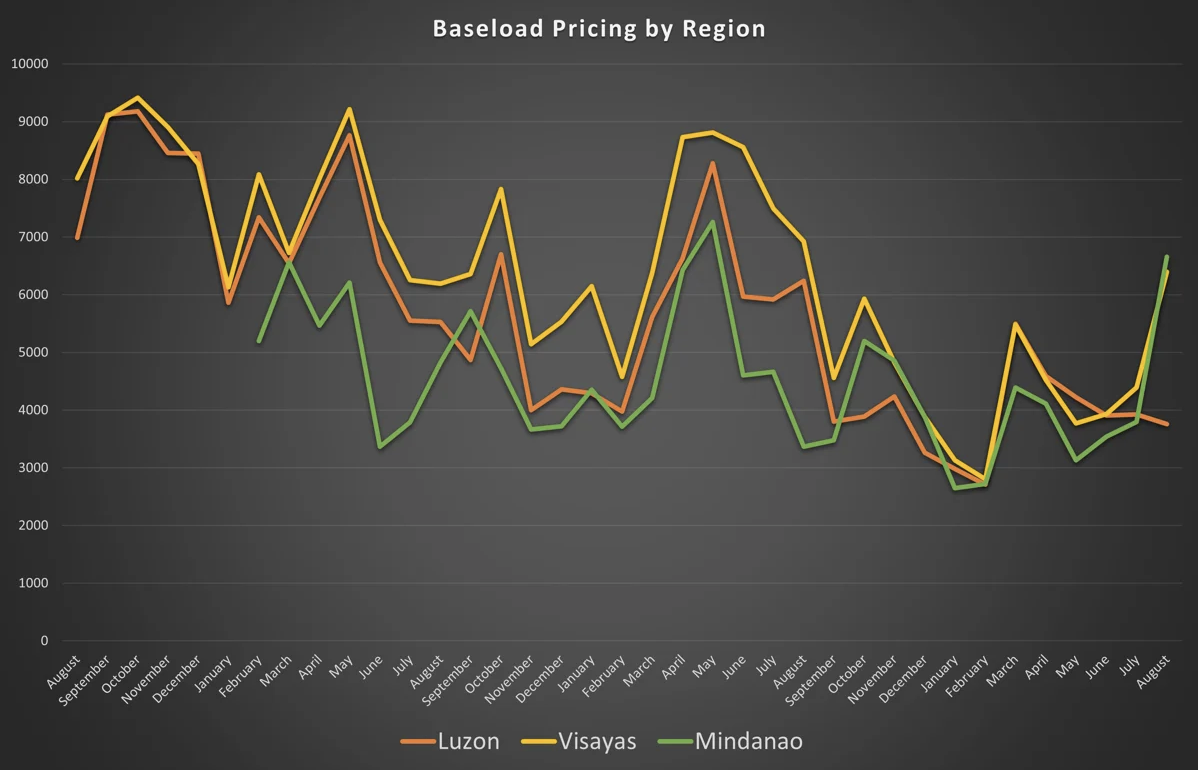
#1 Baseload Prices by Region
August saw some fireworks in the first half of the month. Visayas and Midanao took the lead higher with tight reserves. Luzon saw more modest spikes at the beginning of the month and ultimately wet conditions and holidays kept a lid on the monthly average. Midday continues to average well under Baseload. We expect Midday to continue deteriorate as total load declines into year end but new facilities continue to get energized.
As we step into September, prices have abated significantly with much looser conditions. Our early look has September Luzon Baseload coming in around 2800, challenging February's 2712 print to an ugly contest. We are now on negative price watch as load is coming down but RE continues to go up.
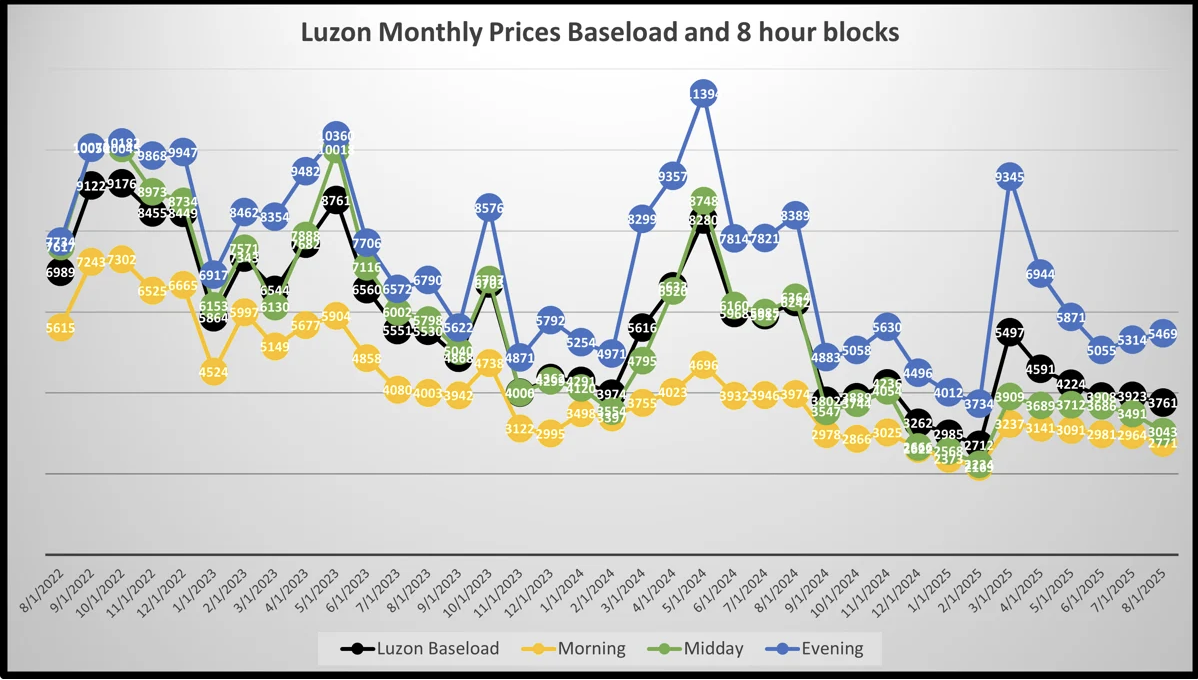
#2 Luzon prices by 8hr time block
In our second graph below, we have plotted the 8 hour time block contracts as well as Baseload. Evening prices had been generally stabilizing since popping during the March outages.
Midday Hours continue dislocating lower on occasion, with steady repricing for the Midday Hours to match Morning Hours. For more developed electricity markets we often see Morning hours trade premium to Midday hours.
Evening hours could see pressure from some of the new gen that is being connected through the balance of the year, but it is a very much wait and see for the evening hours. Demand dropping off into year end, and a healthy hydro situation does not bode well for evening hours.
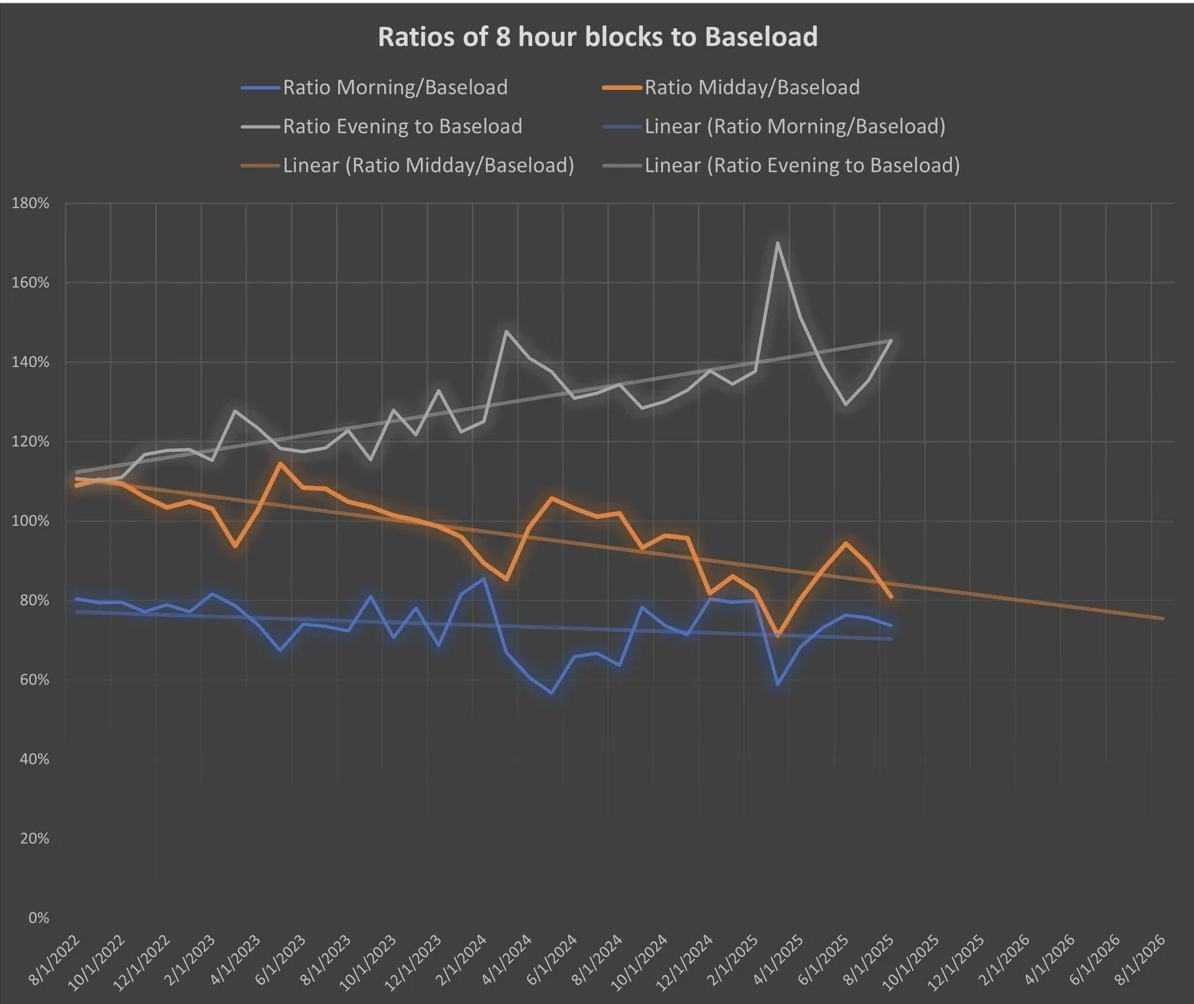
#3 Luzon monthly ratios by product
In our third graph below, we have plotted the ratios of the individual 8 hour products to Baseload. The Evening Hours have retraced to their trendline, mostly driven by a fall in baseload. The panic that existed in the market appears to be abating. Midday and Morning Hours continue to be weak relative to baseload. We saw Evening Hours prices clear roughly 45% over baseload for July and Midday running 20% below baseload.
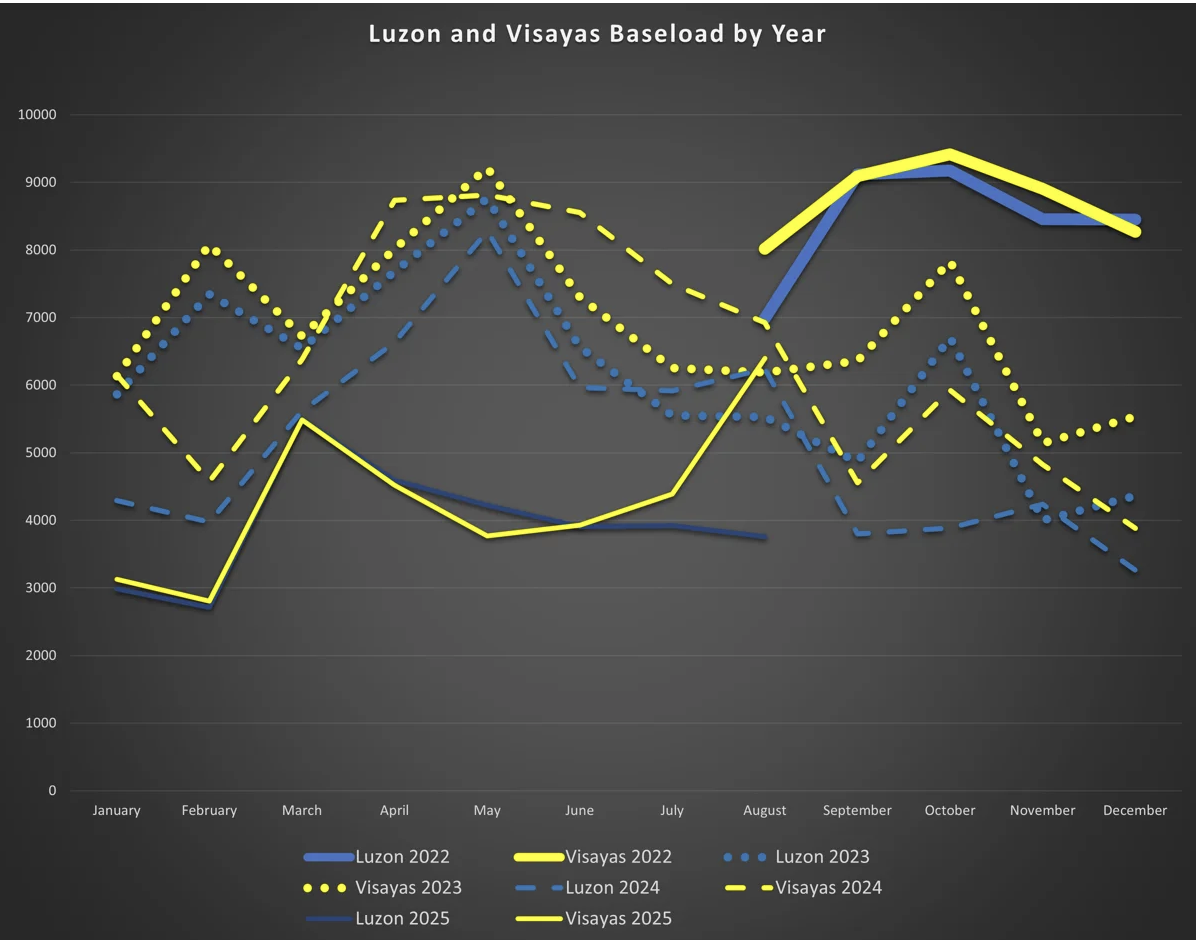
#4 Luzon and Visayas Baseload by year
For Luzon, this year continues to look significantly different from the last few years. August continued the weakness after the brief, outage driven, spike in the first half of the month. On the year, Baseload is averaging under 4000, or a full 1800 php below last year. What does this mean for the balance of the year and into 2026??? Will 2025 average in the 3s? Our estimate is that Cal 25 will average 3500 as prices drop off into year end.
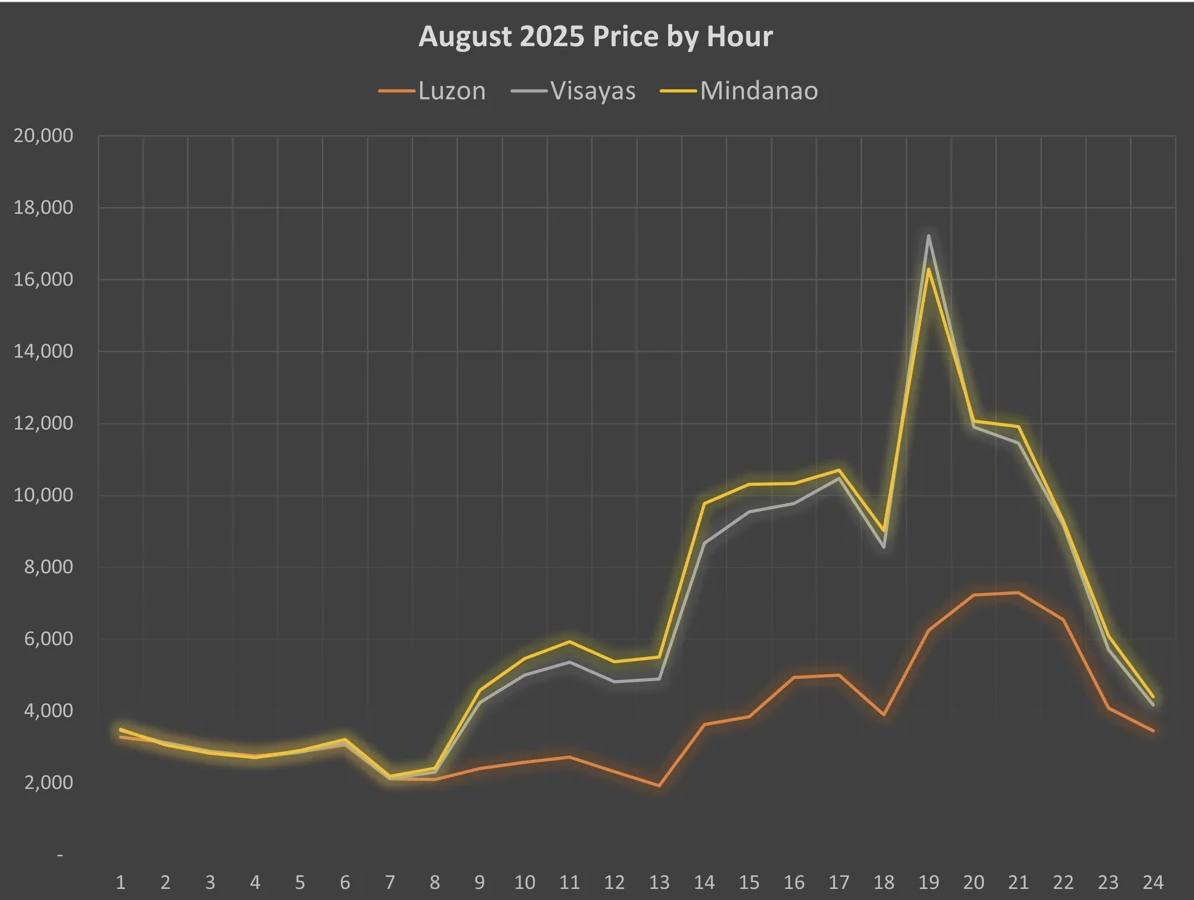
#5 Hourly Prices by Region
Below we have plotted hourly prices by region. Note the massive gap that opened up during higher demand hours in Visayas and Mindanao vs Luzon. Also interesting to note is that all three grids are frequently trading the same price for the Morning Hours.
If you are interested in learning more about our data analysis, please don't hesitate to contact us at [email protected].
New Market Participants!
We continue to add market participants and expand the number of approved counterparties for the GTM market.
As a reminder, all market participants must have net assets in excess of SGD$10mm to become approved market participants.
Market News
As per our usual practice, we have incorporated a selection of recent news stories and emerging trends in the PH electricity market. If there are any noteworthy events you would like us to share, kindly inform us! Enjoy!
MGEN 1,200 MW Atimonan plat to reduce costs ::
Once completed, Atimonan will account for approximately 7% of Luzon’s total electricity demand
Read more here
JNEC Lands Big Philippines:
JNEC will deliver power to support production of plastic components used in camera lenses, printers, laptops, and other electronics
Midday power in the Philippines is getting cheaper—and fast:
A clear trend is emerging in the Philippines: solar power is beginning to warp the midday market.
Read more here
Pumped-storage and hydro power:
Aboitiz and others secure BCK hydropower facility from PSALM
Meralco bills likely to drop in September:
Meralco customers are poised to see lower electricity rates in September
DOE pushes local gas with new oversight committee:
Under the rules, power plants must use local natural gas first, resorting to imported liquefied natural gas (LNG) only when domestic supply is insufficient
Coal price outlook:
Newcastle coal futures are selling off to $105/ton and testing lower
Joining the GTM Marketplace is free.
We highly encourage you to connect with other potential participants who haven't yet joined this thriving marketplace. It's an incredibly efficient way to enhance the liquidity on Green Tiger Markets. If there's a specific company you believe would be a valuable addition to our marketplace, introducing them warmly can truly make a significant impact.
Stay safe and thank you for your business!
-John Knorring, CEO Green Tiger Markets
The views contained in this newsletter are my own opinion and should not be considered investment advice or relied upon to make investment decisions. Disclaimer.
