
Green Tiger Markets PH Electricity August Update
Dear Green Tiger Market Client,
In recent weeks a number of PH energy companies reported their Q2 and H1 financial results to the PSE and investor community. These reports provide an interesting view into the current market landscape. Multiple companies reported margin pressure from lower spot prices.
For reference, a company with 100 MW baseload capacity going into WESM could have generated PHP 600mm greater revenue for the first half of the year had they put on a hedge at market prices on GTM. Regular readers of this newsletter may recall that there were bids as high as 5.5php/kwh and higher for calendar year 2025 and its components on the GTM platform leading up to the start of the year.
Through July, Luzon Baseload has averaged just under 4Php/Kwh for the Load Weighted Average Price. Last year, the first 7 months averaged approximately 5.8P/Kwh. A ~30% decline year on year. There are many causes for the decline in prices, notably:
More dispatchable capacity
More RE installed capacity
A much stronger Hydro situation
Lower Newcastle and ICI3/4 prices
Lower weather related demand with "normal" temps
Greater connectivity in the grid
Because the supply/demand balances are so much weaker year on year, outages, when they do happen, are much less impactful. One of the best indicators of tightness in the market is how frequently the market needs to run expensive oil based generation. In the last 3 months, oil based generation has amounted to 121Gwh. For the same period last year, 542 GWh were dispatched.
Looking to the future, where might prices head? Based on the six factors that were more bearish in 2025 than 2024, we would expect that 1 and 2 will continue to expand (a bearish indicator), 3 will likely be around flat as Hydro is running at "normal" levels now, 4 might break a little bullish as Coal prices have been creeping higher, 5 will likely be around flat as this year is a "normal" year and 2026 is not expected to be El Nino, and lastly 6 will likely break in the bearish direction as more NGCP projects get completed.
With so many shifting variables impacting prices, remaining unhedged incurs a big financial risk for companies and their shareholders. For any company with large WESM exposure interested in reducing this risk, we would invite you to start small, consider it as a trial, and offer 10-15% of your unhedged portfolio into the forward market for each of the months and quarters over the next 12-24 months. Any matched orders will improve your overall financial security. Additionally, getting active in the hedging market for a small percent of the merchant portfolio helps to build up the internal processes and ‘muscle memory’ in your organization to gradually increase your hedged portfolio in the future.
With many Philippines energy companies already using financial hedges for currencies, interest rates, and fuel commodities, we strongly recommend expanding risk management practices to include electricity price hedging now that the GTM market is available.
As we continue to spread the word on the benefits of financial hedging, we are participating in more industry conferences in the Philippines. Our Head of Business Development Andrew Koger recently presented at First Gen’s Renewable Energy Conference on August 7 and 8 and received substantial interest from the audience during the networking sessions. We are also presenting at the American Chamber of Commerce’s Energy Forum this Thursday August 14 and will be attending additional events later in the year. If you see us at any conferences around the Philippines, please come say hello. We always enjoy discussing the energy market and meeting current and prospective clients.
In particular, we will be co-hosting an event with the Energy Lawyers Association of the Philippines (ELAP) on September 17 to provide a special intro session on financial derivatives for Philippines energy lawyers. If you would like to have your legal team attend, please feel free to reach out to us or ELAP for more details.
Interested in learning more about how to improve supply/demand balance forecasting?
Areas of Focus for Hedging in May
Continued buyside interest from RES to lock in margins
Continued interest in outright months and strips in 2025
Sellers are sniffing around in 2026, and now 2027
We are working several orders for 2025 Luzon baseload power. Midday hours are generally being offered at 15-25% below baseload prices while bids have been scarce. Evening hours are generally being bid at 130-150% of Baseload, with offers being scarce. Here are some of the most intriguing opportunities, all values in quoted in PHP/Mwh:
October - December Baseload: 4000 bid @ 4400 offered
August 25 - July26: 4500 bid @ 5000 offered
Cal 26 4500 bid @ 5100 offered
We're witnessing a increase in activity from a variety of participants looking to lock in prices for the balance of the year. In general, the bids that we are seeing are quite strong, often well in excess of last year's prices
Live pricing levels
As prices continue to fluctuate with the changing market dynamics, we kindly request that you contact us directly for the most up-to-date and comprehensive list of orders we are currently handling. Thank you!
Meet with a GTM Risk Management Specialist
In a quick phone call we can help stabilize your future.
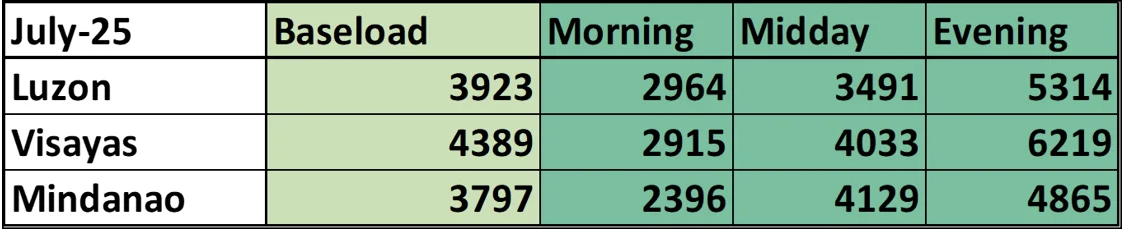
Since our last update, the Philippines electricity market has been relatively sanguine. July priced out nearly identically to June. Evening prices continue to slowly moderate, and Midday continues to average 500-600 pesos under Baseload. We expect Midday to deteriorate as total load declines into year end but new facilities continue to get energized.
As we step into August, prices have rebounded a bit with a few outages. Our early look has August coming in around 4500, stronger than where the forwards were just a few weeks ago. We had been expecting to see some stress in the grid for summer load, but those fears have yet to realize. Now the market is on unplanned outage watch.
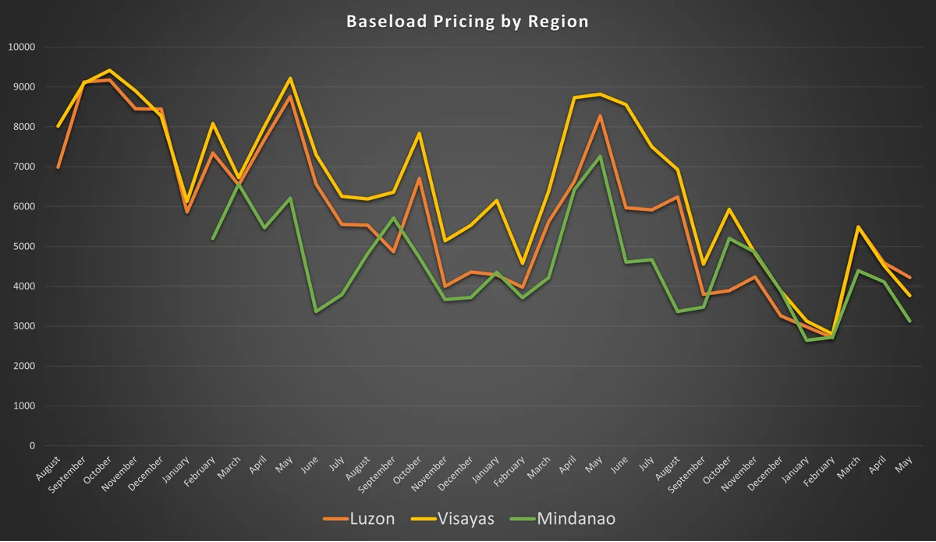
#1 Baseload Prices by Region
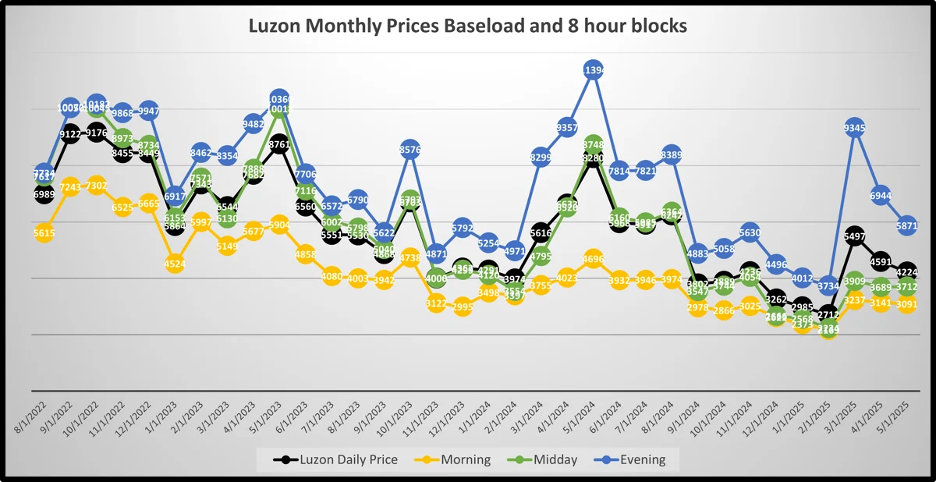
In our second graph below, we have plotted the 8 hour time block contracts as well as Baseload. Evening prices had been generally trending lower since popping during the March outages. The downtrend paused in July and will likely stabilize given the incremental solar coming to the market and the new gas fired thermal plants will have fewer premium hours to amortize their fixed costs over. There has been virtually zero need for diesel to run
Midday Hours continue dislocating lower on occasion, with steady repricing for the Midday Hours to match Morning Hours. For more developed electricity markets we often see Morning hours trade premium to Midday hours.
Evening hours could see pressure from some of the new gen that is being connected through the balance of the year, but it is a very much wait and see for the evening hours.
#2 Luzon prices by 8hr time block
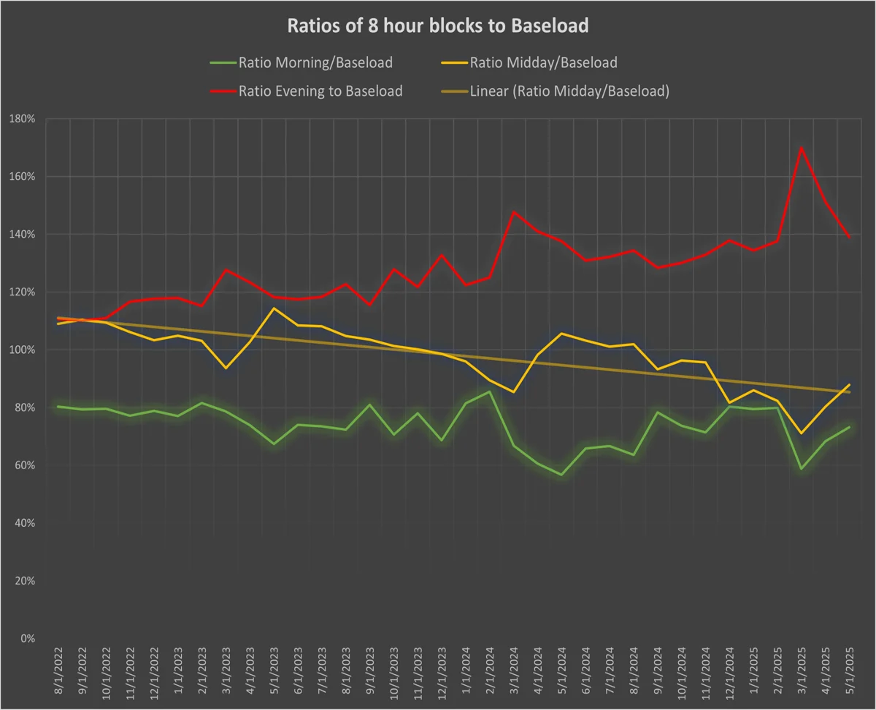
In our third graph below, we have plotted the ratios of the individual 8 hour products to Baseload. The Evening Hours have retraced quite a lot as there have been very few hours where diesel is required. The panic that existed in the market appears to be abating. Midday and Morning Hours continue to be weak relative to baseload, but given the overall decline in prices, they appear a bit stronger on a relative basis. We saw Evening Hours prices clear roughly 35% over baseload for July and Midday running 10% below baseload.
#3 Luzon monthly ratios by product
Year-on-Year comparison
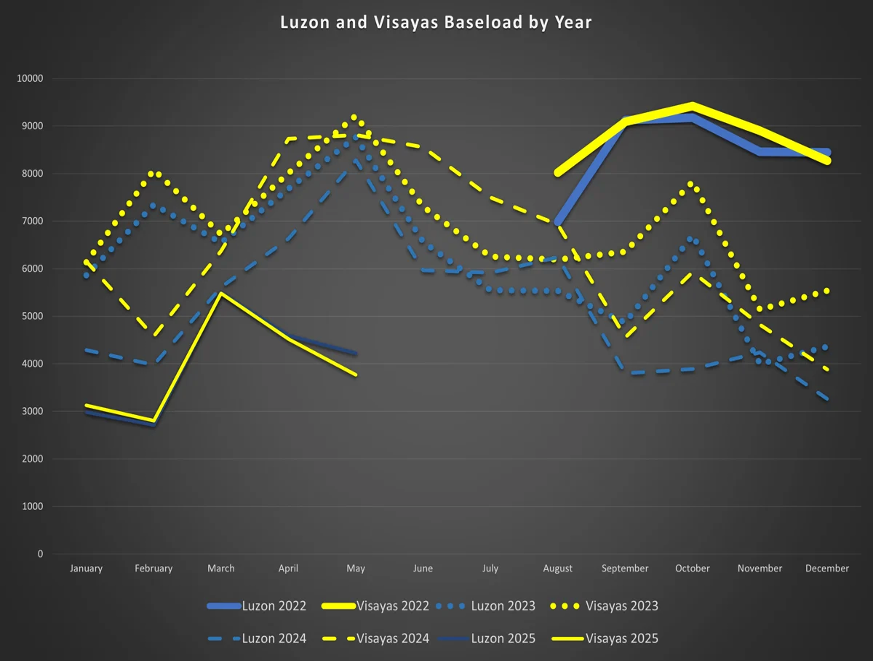
This year continues to look significantly different from the last few years. July continued the weakness after the brief, outage driven, spike in March prices. On the year, Baseload is averaging under 4000, or a full 1800 php below last year. What does this mean for the balance of the year and into 2026??? Will 2025 average in the 3s? Typically the second half of the year prices lower than the first half.
#4 Luzon and Visayas Baseload by year
Hourly Pricing
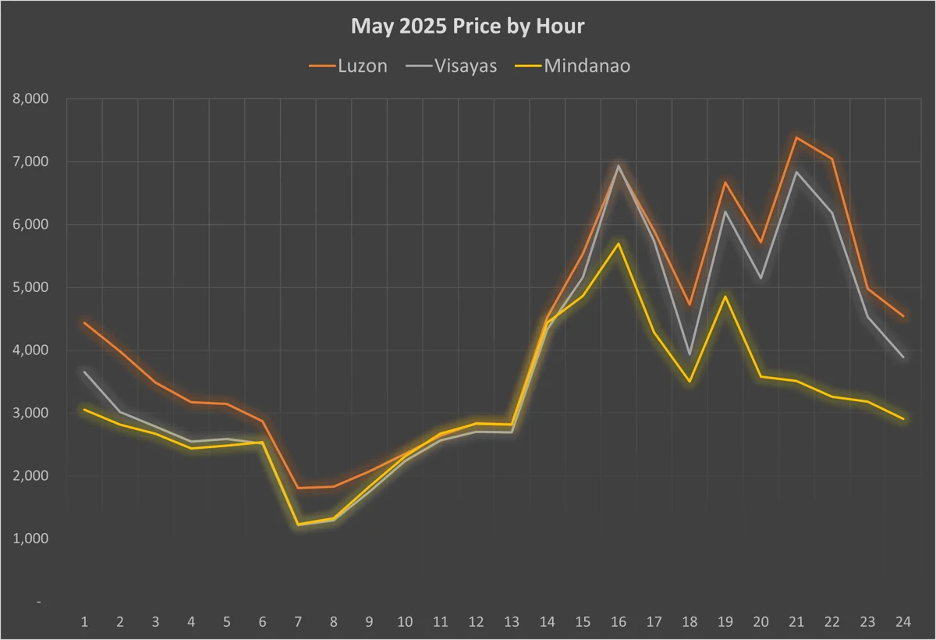
Below we have plotted hourly prices by region. Last month saw an overall flattening of the evening relative to months past. The "Duck Curve" was not as pronounced this past month. Also interesting to note is that all three grids are frequently trading the same price.
#5 Hourly Prices by Region
If you are interested in learning more about our data analysis, please don't hesitate to contact us at [email protected].
New Market Participants!
We continue to add market participants and expand the number of approved counterparties for the GTM market.
As a reminder, all market participants must have net assets in excess of SGD$10mm to become approved market participants.
Market News
As per our usual practice, we have incorporated a selection of recent news stories and emerging trends in the PH electricity market. If there are any noteworthy events you would like us to share, kindly inform us! Enjoy!
Semirara reports 41% decline in Q2:
59% of electricity was sold on the spot market
Read more detail about the earnings report here
ACEN H1 2025 Net Income Falls to PHP763M:
Stripping out one-time items, net income fell by 24 percent, as the company faced lower spot market prices and increased depreciation costs.
First Gen holds H1 2025 earnings at USD 151M
EDC posted lower recurring net income in the first two quarters due to reduced spot market prices.
Read more here
Ilijan Power Plant Under Scrutiny as ERC Probes SPPC for Market Abuse:
(SPPC) to explain its disconnection of the 1,200-megawatt Ilijan Power Plant from the grid in June 2022. The disconnection coincided with WESM rising by more than 30%.
Coal price outlook:
Newcastle coal futures are hovering just above $115/ton and stabilizing
Why Philippine Electricity Prices Remain Low in 2025:
The trend reflects structural shifts in supply, demand, and the evolving economics of power generation.
Joining the GTM Marketplace is free.
We highly encourage you to connect with other potential participants who haven't yet joined this thriving marketplace. It's an incredibly efficient way to enhance the liquidity on Green Tiger Markets. If there's a specific company you believe would be a valuable addition to our marketplace, introducing them warmly can truly make a significant impact.
Stay safe and thank you for your business!
-John Knorring, CEO Green Tiger Markets
*The views contained in this newsletter are my own opinion and should not be considered investment advice or relied upon to make investment decisions. Disclaimer.
