
Green Tiger Markets PH Electricity October Update
Dear Green Tiger Market Client,
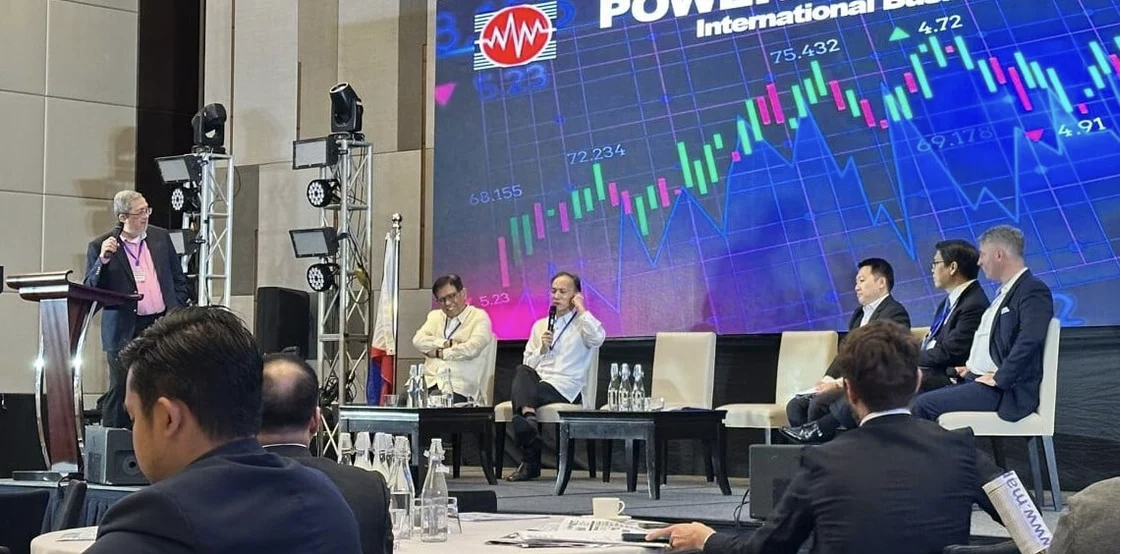
It was wonderful to see so many of you a week ago in Metro Manila. There truly is no substitute for in person meetings. It was great to hear different views of the market and where people are losing sleep. It was also great to participate in PowerTrends 2025 panel discussion. Thank you to Guido Delgado for moderating a wonderful discussion. It was great to share the stage with SEC Commissioner Lim and with leaders of the Philippines banking community. I was most excited to hear that banks are beginning to consider alternatives to PSAs in order to secure financing.
Volatility is everywhere in the Philippines Electricity Market. We see intraday volatility when reserve margins get tight. We see Visayas and Mindanao dislocate from Luzon and follow their own price paths. And we see volatility from one month to the next. Who would have thought that September would be the lowest month?
The Luzon electricity market last month was marked by strikingly low prices. Wholesale spot prices averaged PHP 2.6 per kilowatt-hour, their lowest in several months—a result of modest supply growth alongside a mild contraction in demand. The resulting supply margin widened, leaving the grid comfortably oversupplied and prices deflated, much to the relief of consumers.
The Philippines' electricity supply-demand balance is expected to remain loose through the foreseeable future, as system-wide supply growth continues to outpace gains in demand. Forecasts for 2025-2026 suggest that total installed generation capacity will expand further, with several thousand megawatts of additional capacity coming online, most of it sourced from renewables.
Meanwhile, demand is projected to increase, but at a slower and more predictable rate, especially as economic growth normalizes and consumption remains somewhat restrained. This implies that the wide supply margin seen throughout 2025 will persist, keeping wholesale prices low and market equilibrium tilted in favor of buyers rather than generators.
Many generators reliant on spot market revenues—particularly those without long-term bilateral contracts—will see squeezed cash flows as prices remain subdued. Unhedged players could face mounting financial stress, especially if fixed costs remain high and planned renewable capacity additions further dilute price recovery prospects. In particular, independent power producers betting on spot price rebounds will be most exposed to volatility and downside risk over the coming quarters.
Interested in learning more about how to improve supply/demand balance forecasting?
Areas of Focus for Hedging
Stable forward pricing
Steady bids from RES and Bulk Consumers
Sellers are sniffing around in 2026, and 2027
The forwards have stabilized despite the large selloff in September spot.
Cal 26 4200 Bid @ 4500 Offered
Cal 27 4200 Bid @ 4700 Offered
Long term midday (5 years or more) offered at 4100.
We continue to witness a strong increase in activity from a variety of participants looking to lock in prices for next year. We have registered a handful of new clients in the last two months, and they are becoming more active.
Live pricing levels
Given the fast-paced shifts in market pricing, we encourage you to reach out directly for the latest and most detailed list of active orders. Connect with us to stay ahead and access the most current opportunities—thank you!
Meet with a GTM Risk Management Specialist
In a quick phone call we can help stabilize your future.
Market Data and Commentary
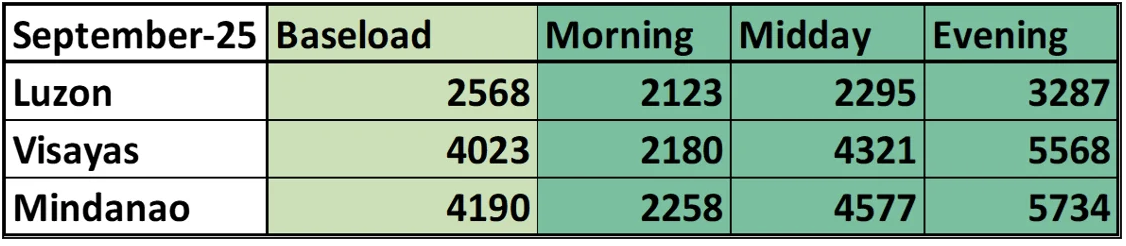
#1 Baseload Prices by Region
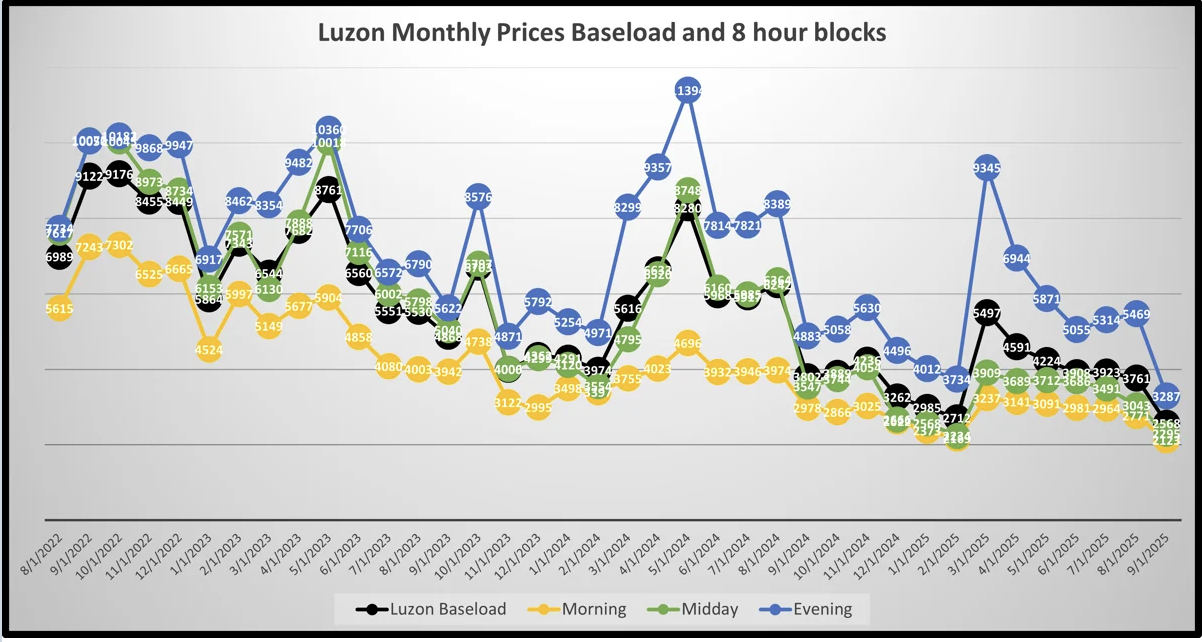
September saw continued weakness in Luzon spot with the lowest settle in several years. Visayas and Mindanao acted like the HVDC line did not exist and took an entirely different price path. Luzon saw muted conditions this month and ultimately wet conditions kept a lid on the monthly average with hydro output on a new high. Midday continues to average well under Baseload and we expect Midday to continue deteriorate as total load declines into year end but new facilities continue to get energized.
As we step into October, prices have risen significantly with evening prices leading the way higher. Our early look has October Luzon Baseload coming in around 4000. We are on negative price watch as load is coming down but RE continues to go up.
#2 Luzon prices by 8hr time block
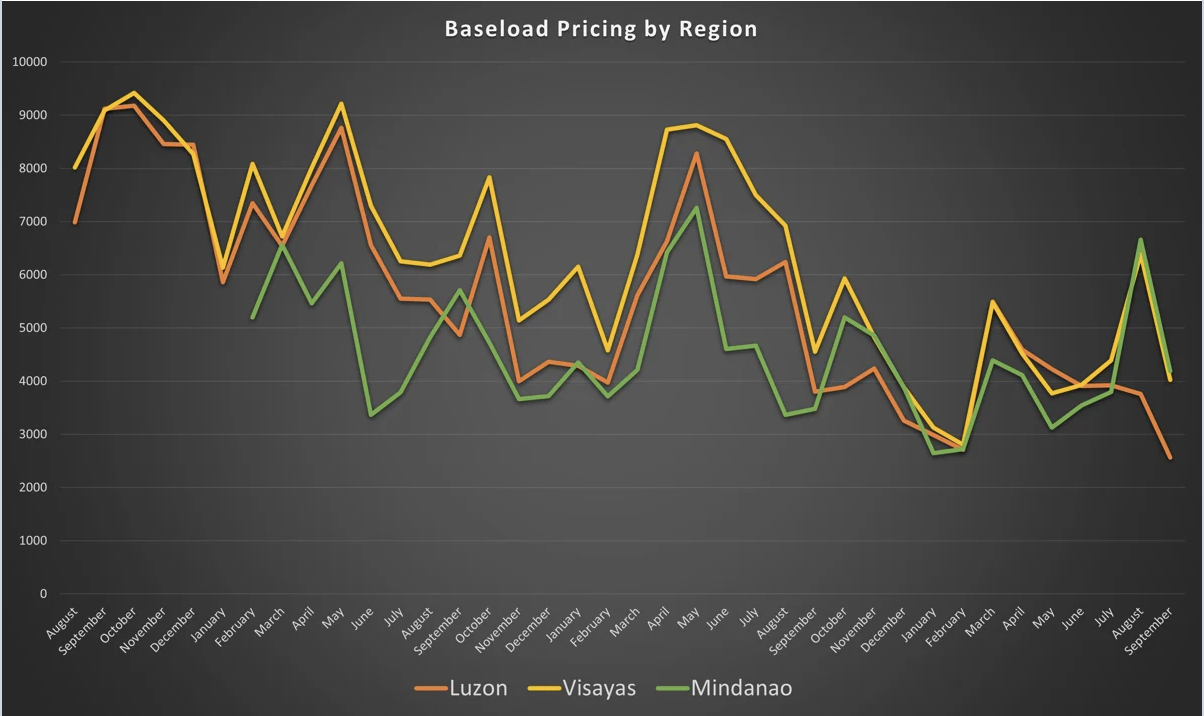
In our second graph below, we have plotted the 8 hour time block contracts as well as Baseload.
Midday Hours continue dislocating lower on occasion, with steady repricing for the Midday Hours to match Morning Hours. Luzon added nearly 10% more solar for the month of September. For more developed electricity markets we often see Morning hours trade premium to Midday hours. Beware uncontracted solar!
Evening hours could see pressure from some of the new gen that is being connected through the balance of the year, but it is a very much wait and see for the evening hours. Demand dropping off into year end, and a healthy hydro situation does not bode well for evening hours.
#3 Luzon monthly ratios by product
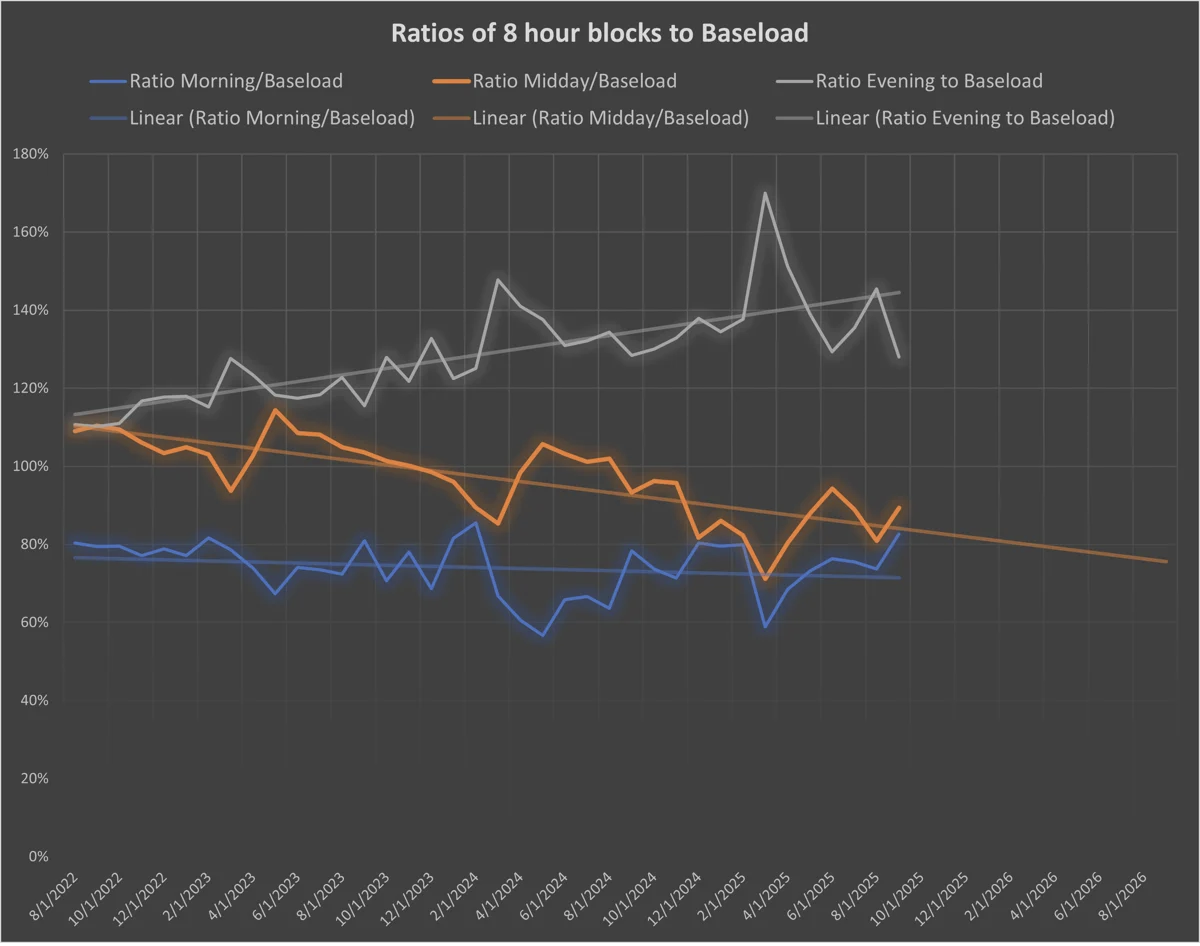
In our third graph below, we have plotted the ratios of the individual 8 hour products to Baseload. The Evening Hours abated in September, mostly driven by a rise in reserve margins. The panic that existed in the market appears to be abating. Midday and Morning Hours continue to be weak relative to baseload. We saw Evening Hours prices clear roughly 30% over baseload for July and Midday running 15% below baseload.
#4 Luzon and Visayas Baseload by year
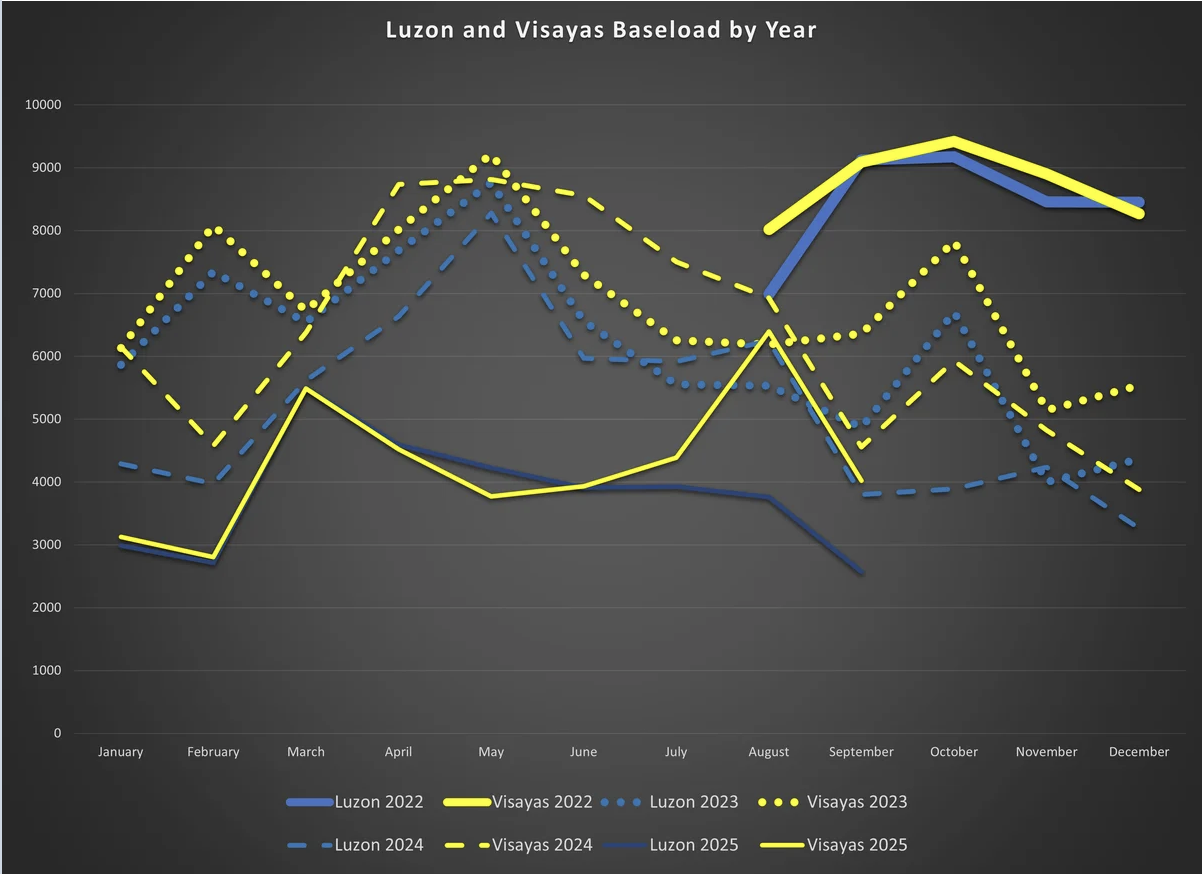
For Luzon, this year continues to look significantly different from the last few years. Visayas though might be heading back to '23-'24 pricing. On the year, Baseload is averaging under 4000, or a full 1800 php below last year. What does this mean for the balance of the year and into 2026??? Will 2025 average in the 3s? Our estimate is that Cal 25 will average 3500 as prices drop off into year end.
#5 Hourly Prices by Region
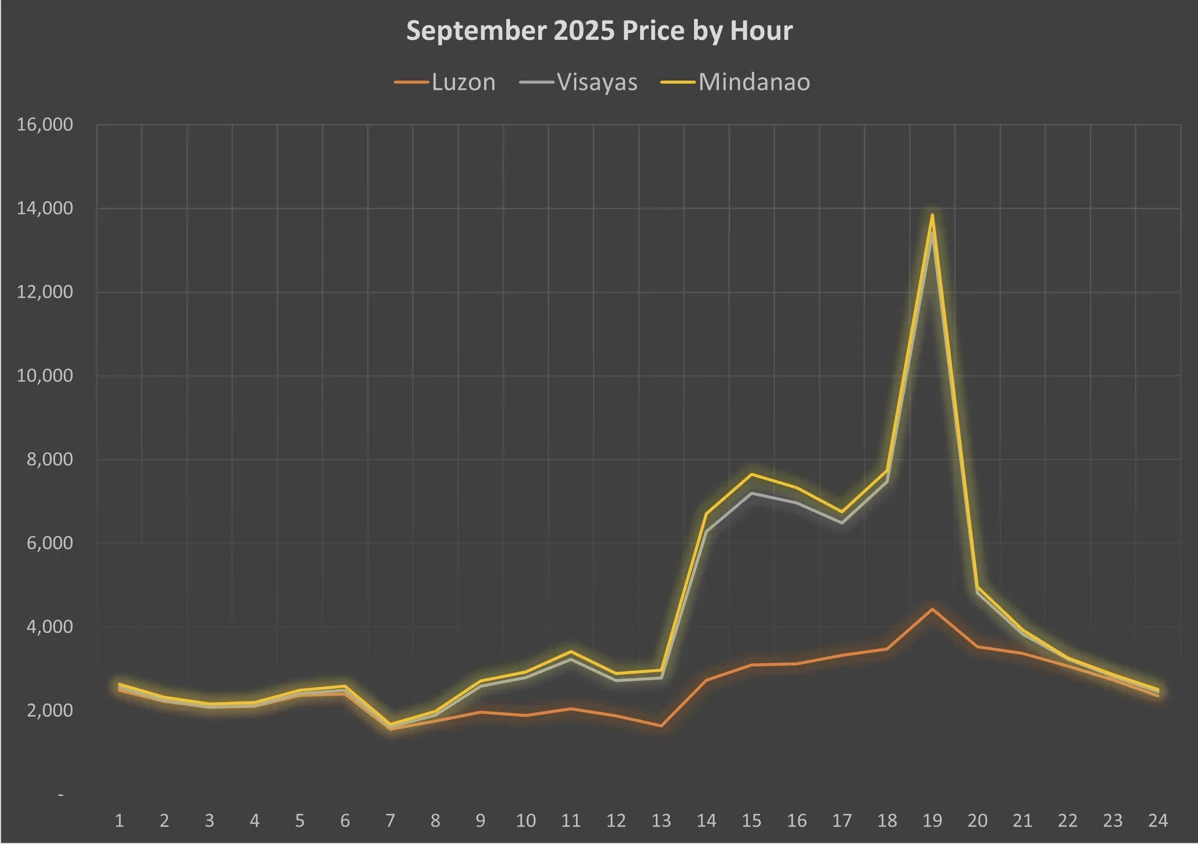
Below we have plotted hourly prices by region. Note the massive gap that opened up during higher demand hours in Visayas and Mindanao vs Luzon. Also interesting to note is that all three grids are frequently trading the same price for the Morning Hours.
If you are interested in learning more about our data analysis, please don't hesitate to contact us at [email protected].
New Market Participants!
We continue to add market participants and expand the number of approved counterparties for the GTM market.
As a reminder, all market participants must have net assets in excess of SGD$10mm to become approved market participants.
Market News
As per our usual practice, we have incorporated a selection of recent news stories and emerging trends in the PH electricity market. If there are any noteworthy events you would like us to share, kindly inform us! Enjoy!
Meralco rates up in October:
Despite much lower YoY spot prices, retail rates continue to move higher
Read more here
ACEN injects PHP 1.9B into NAREDCO solar operations:
Once completed, the Cagayan North Solar Power Plant will have a total capacity of 133.464 MWp (DC)
DOE proposes policy letting power firms build transmission lines:
To help speed up the completion and delivery of power projects across the country
Read more here
ERC moves to finalize rules for energy storage integration:
The rules will set standards for ownership models, interconnection protocols, safety, and integration into the Philippine Grid Code (PGC), Distribution Code (PDC), and Wholesale Electricity Spot Market (WESM).
ERC approves PHP 14.25-B grid link for MTerra Solar Project:
The PHP 200-billion MTerra Solar Project will deliver up to 850 MW of baseload solar power once operational
DOE unveils key energy updates:
They covered indigenous gas exploration, waste-to-energy auctions, electric vehicle policy, and grid resiliency efforts
Coal price outlook:
Newcastle coal futures are selling off to $105/ton and testing lower
Joining the GTM Marketplace is free.
We highly encourage you to connect with other potential participants who haven't yet joined this thriving marketplace. It's an incredibly efficient way to enhance the liquidity on Green Tiger Markets. If there's a specific company you believe would be a valuable addition to our marketplace, introducing them warmly can truly make a significant impact.
Stay safe and thank you for your business!
-John Knorring, CEO Green Tiger Markets
The views contained in this newsletter are my own opinion and should not be considered investment advice or relied upon to make investment decisions. Disclaimer.
