
Green Tiger Markets: September Electricity Market Review
Dear Valued Client,
Regional supply reliability remained a concern during the September billing period. Continued outages and insufficient dependable local generation kept the Visayas under pressure. By September 22, the DOE was still prioritizing the return of unavailable plants, while outages in Mindanao had reduced power available for transfer to the Visayas to around 50 MW—highlighting the difference between transmission capacity and electricity available to move across it.
The ERC’s decision to calculate the WESM Secondary Price Cap separately by region, effective from the August billing period onward, also changed settlement dynamics. Previously, lower Luzon prices could prevent the cap from triggering despite sustained high prices in the Visayas and Mindanao. Regional caps can limit settlement prices, but they do not resolve the underlying shortages—a distinction that matters when assessing procurement costs and hedge performance.
Luzon saw a more encouraging development: Malampaya gas resumed supplying the 1,200 MW Ilijan plant under an interim agreement beginning September 1. Prime Energy estimated that domestic gas could reduce generation charges by about PHP 0.36/kWh for the supplied generation, not the overall WESM price.
For generators, retailers and large users, September reinforced the need to manage physical supply and financial exposure separately. Replacement power may be scarce when neighboring grids are also tight, while regulatory interventions can change settlement outcomes without improving availability.
Combining dependable physical supply with clearly defined spot exposure and GTM forward hedges can make costs and revenues more predictable. The goal is not to eliminate every price movement, but to limit the financial impact of shortages and replacement-power costs, supporting more stable margins and budgets.
Interested in learning more about how to improve supply/demand balance forecasting?
Areas of Focus for Hedging
Forward prices continue to press higher in Luzon
1 year Baseload Luzon strips starting over the next few months have been in the mid 5's
Two year strips are 5000 bid.
Continued desire to sell Midday hoursout the curve at a discount to Baseload
Cal 27 5000 Bid @ 5500 Offered
Participation remains strong across the forward market as generators and consumers move to secure value at today’s elevated levels. Generators are layering in hedges to capture higher prices, while consumers are locking in protection against further increases if the Middle East conflict continues to put upward pressure on the curve. Different priorities, one shared focus: managing exposure before the market moves again.
Live pricing levels:
In a fast-moving market, a price snapshot only tells part of the story. Connect with our desk for a live view of active orders, current pricing, and selected opportunities. We’ll help you see what’s actionable now so you can make your next hedging decision with a clearer picture of the market.
Meet with a GTM Risk Management Specialist
In a quick phone call we can help stabilize your future.
Market Data and Commentary
Philippine power prices remain high, with costly fuel and widespread outages keeping the market on edge. Hopes that new solar capacity and battery storage will deliver swift price relief are fading. Through year-end, shifting coal prices, geopolitical tensions, and El Niño conditions could drive sharp moves in either direction. Below, we weigh the forces that could keep prices elevated against those that could bring them lower.
Bullish factors
Longer-term energy disruption could keep the market tight and support prices.
Elevated coal prices for the balance of the year would raise marginal generation costs.
A strong El Niño adds upside risk as El Niño conditions are typically hotter and drier than normal, which can increase AC demand and reduce hydro output.
Continued outages could keep prices supported.
Bearish factors
The Middle East conflict could end soon which will put downward pressure on energy prices.
Forward prices moved up 20–25% above pre-conflict levels. Prior to the conflict, the market was fairly heavy and felt oversupplied.
Energy supply-chains may prove to be more resilient
A significant amount of solar is already energized and more is expected through year-end.
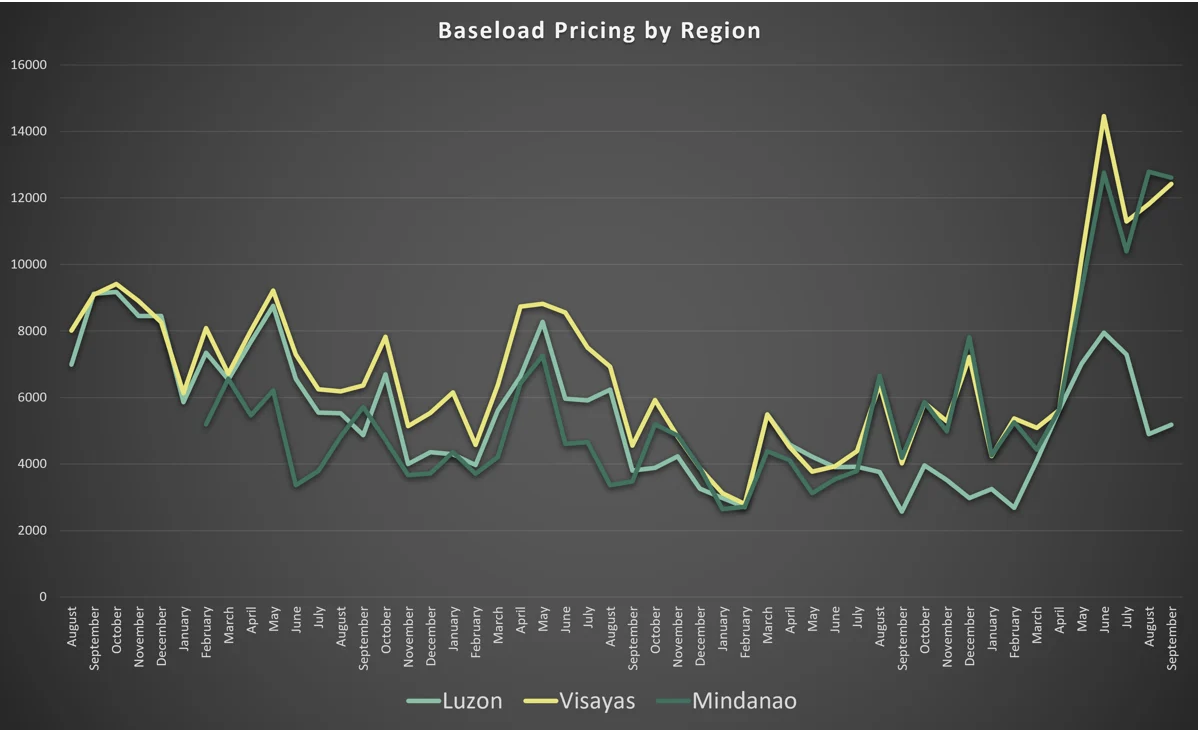
#1 Baseload Prices by Region
Prices stabilized in September in Luzon. Fewer outages and more moderate weather load kept prices in check relative to June/July. Prices observed for Visayas and Mindanao remained extremely high as outages and constrained transmission proved substantial. Note: Graph does not contain all ERC price adjustments for secondary price cap.
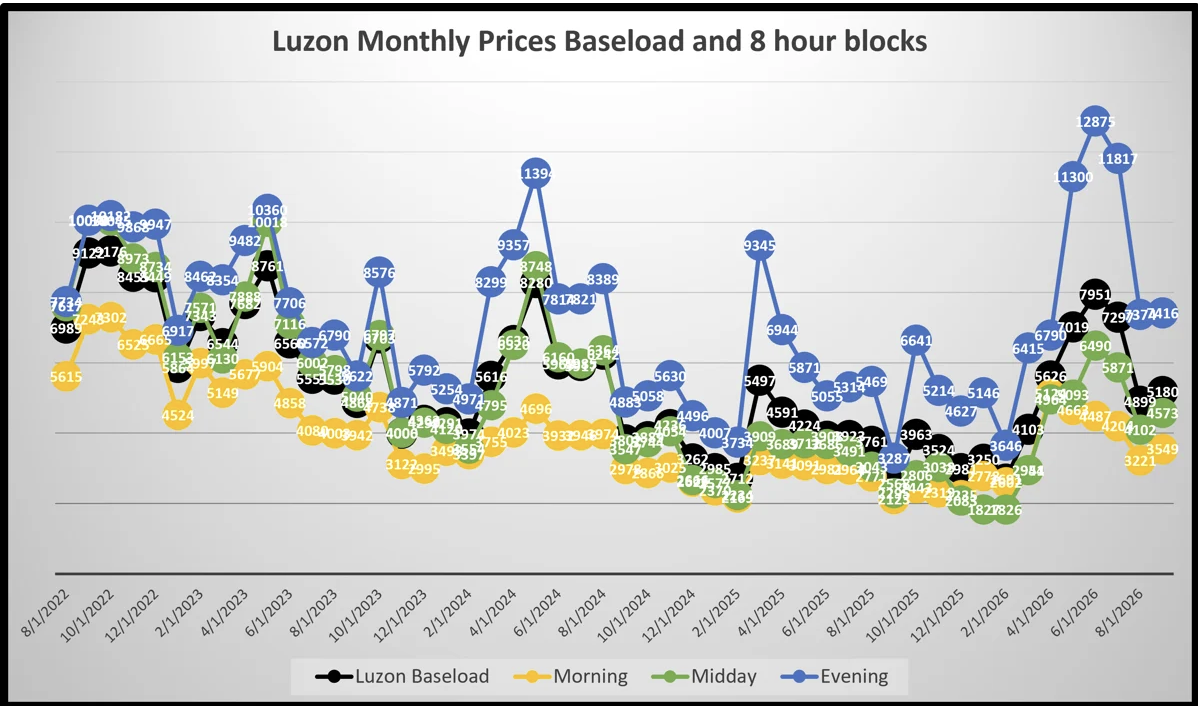
#2 Luzon prices by 8hr time block
In our second graph below, we have plotted the 8 hour time block contracts as well as Baseload.
Similar pricing in September vs August
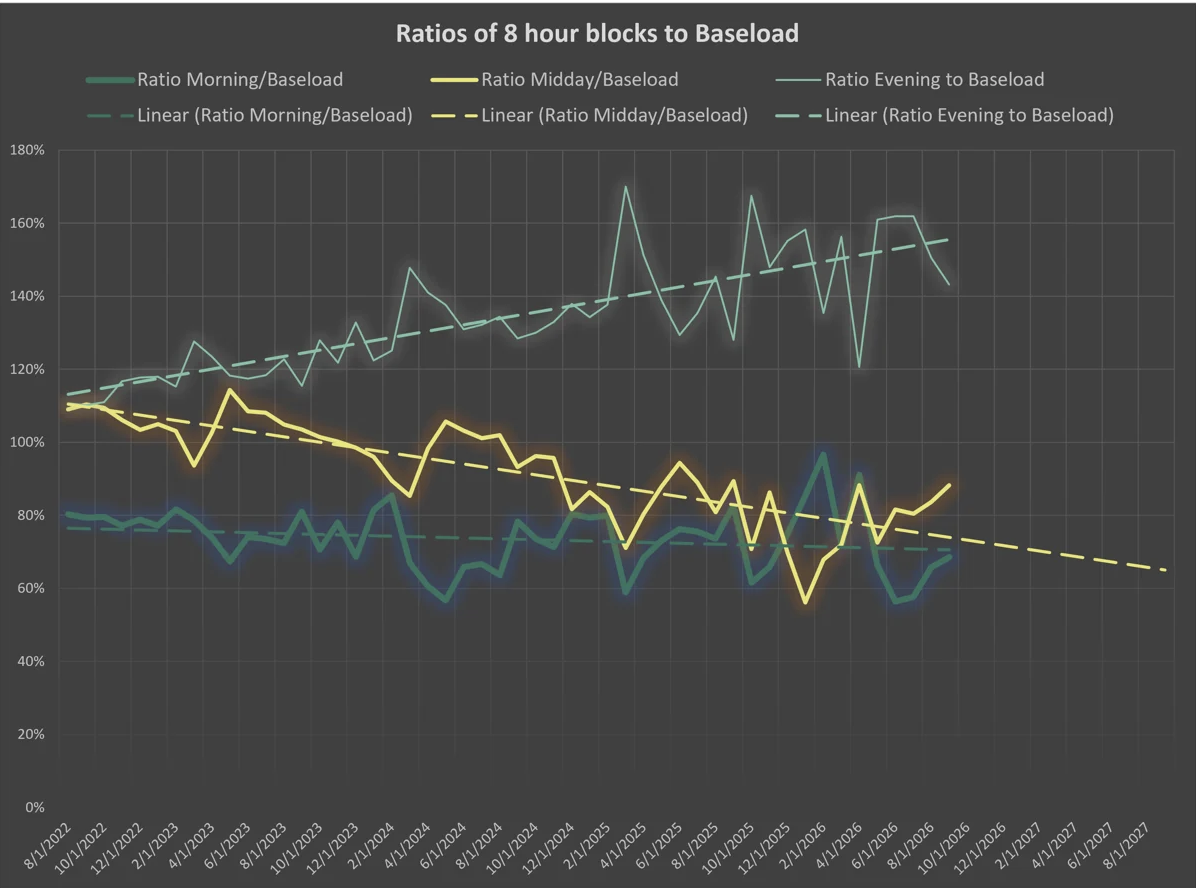
#3 Luzon monthly ratios by product
In our third graph below, we have plotted the ratios of the individual 8 hour products to Baseload.
Midday prices remained robust relative to the longer term duck curve trend. We expect that when loads moderate into year end, we will hear the duck quack. On days with low load, Solar output has been pushing midday prices downward. Evening price remains robust, generally a 50-60% premium to Baseload.
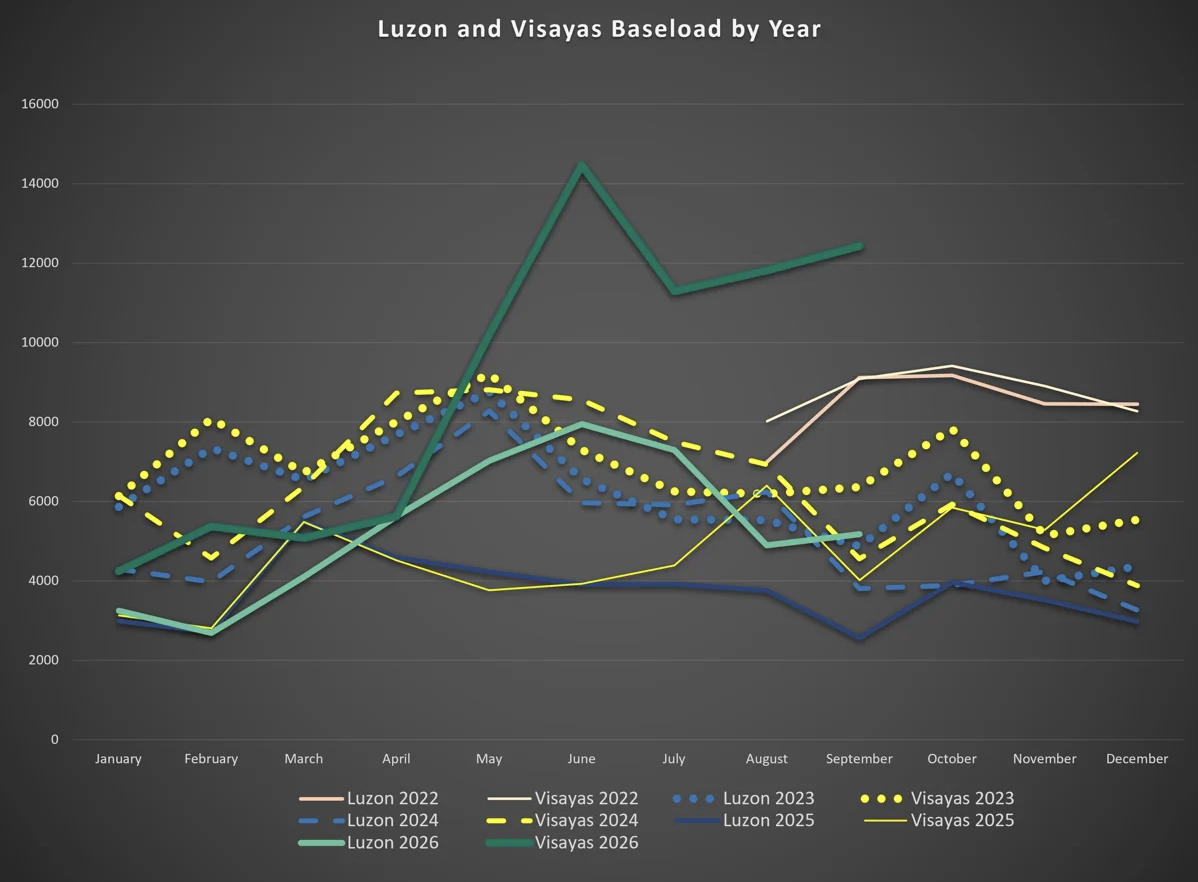
#4 Luzon and Visayas Baseload by year
Visayas remains the story as outages combined with transmission constraints left very few options for the grid. The problem will last until the offline generation comes back. Hopefully that is soon.
Luzon, has eased back into a more "normal" range with prices coming in in line with '23, '24 and '25.
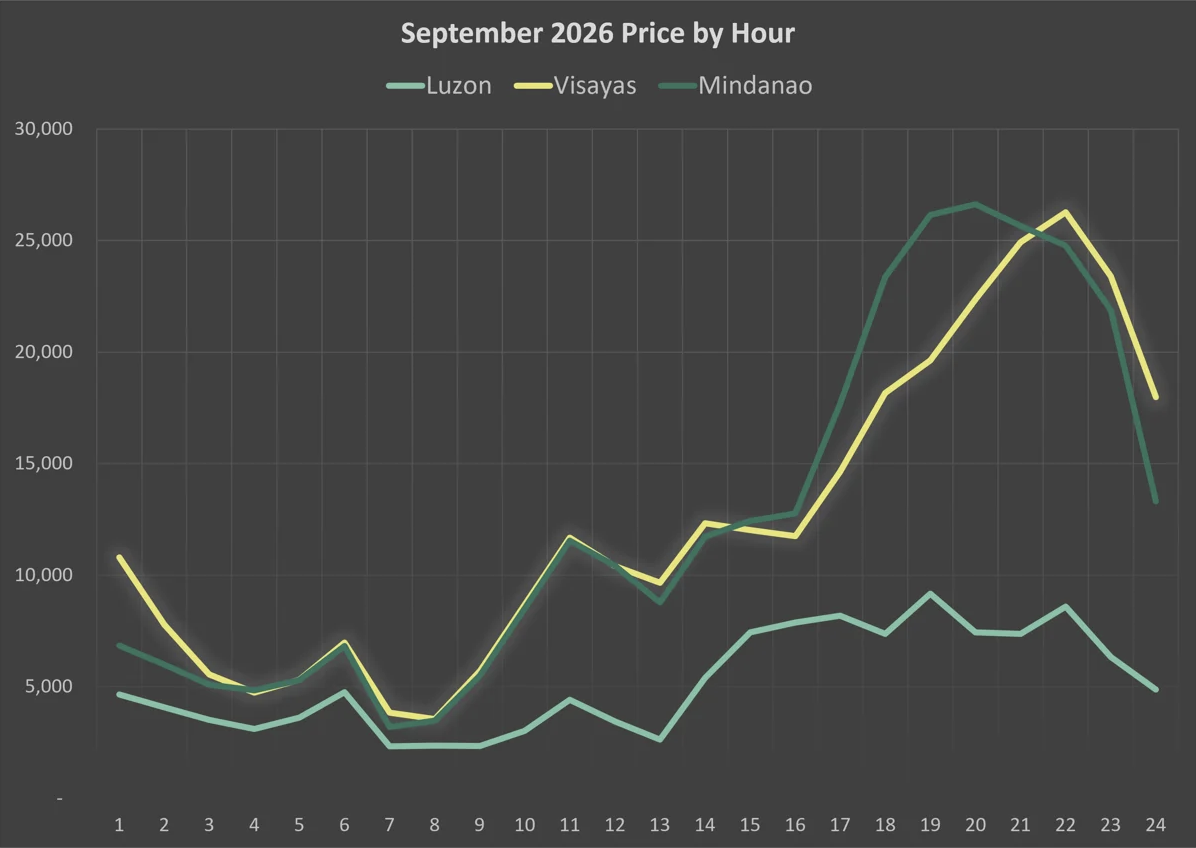
#5 Hourly Prices by Region
Below we have plotted hourly prices by region. Visayas pricing, again, along with Mindanao was something special. Nearly every day cleared the price cap for hour ending 7 pm.
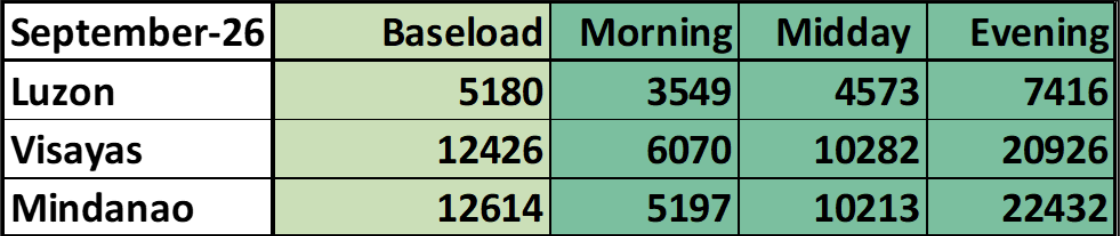
#6 Final settles by segment
Strong pricing in Visayas and Mindanao, more modest in Luzon. An early look into October prices has more of the same.
If you are interested in learning more about our data analysis, please don't hesitate to contact us at [email protected].
New Market Participants!
We continue to add market participants and expand the number of approved counterparties for the GTM market.
As a reminder, all market participants must have net assets in excess of SGD$10mm to become approved market participants.
Market News
As per our usual practice, we have incorporated a selection of recent news stories and emerging trends in the PH electricity market. If there are any noteworthy events you would like us to share, kindly inform us! Enjoy!
ERC suspends reserve market over high power costs, orders overhaul:
Secondary Price Cap in WESM to be applied on a regional basis
Mabuhay Energy says grid constraints limit gains from retail power competition
Affordable generation cannot reach consumers because of transmission constraints.
RCOA Phase 4 opens power choice to 12,491 businesses:
Expanded retail competition lets 12,491 businesses choose suppliers and negotiate electricity contracts.
DOE sees no significant solar decline from El Niño:
Visayas remains vulnerable if supply pressures constrain electricity imports from Luzon and Mindanao
WESM price climbs to PHP 7.43/kWh despite wider supply margin:
Outages and transmission constraints pushed September electricity prices higher despite improved supply margins.
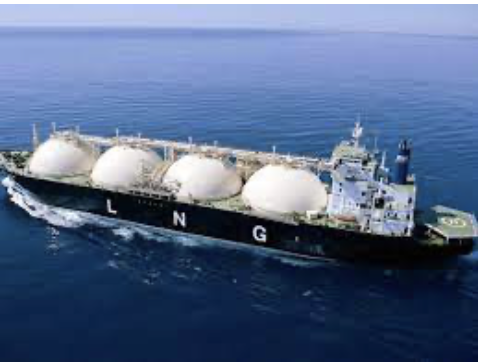
LNG spot price surge deters Asian buyers:
The slump in Asian demand is freeing up cargoes for Europe
Coal price outlook:
Newcastle coal futures are around $150/ton and looking for direction.
Joining the GTM Marketplace is free.
We highly encourage you to connect with other potential participants who haven't yet joined this thriving marketplace. It's an incredibly efficient way to enhance the liquidity on Green Tiger Markets. If there's a specific company you believe would be a valuable addition to our marketplace, introducing them warmly can truly make a significant impact.
Stay safe and thank you for your business!
-John Knorring, CEO Green Tiger Markets
The views contained in this newsletter are my own opinion and should not be considered investment advice or relied upon to make investment decisions. Disclaimer.
