
Green Tiger Markets: March Electricity Market Review
Dear Valued Client,
Since the recent outbreak of conflict in the Middle East, the global energy landscape has been fundamentally upended. Established trade routes have been thrown into disarray, and a new wave of uncertainty and price volatility has swept through the markets. Nowhere is this felt more acutely than in Asia, where economies rely heavily on steady supplies from the Persian Gulf. Crude oil, refined products, liquefied natural gas, and critical petrochemical feedstocks all hinge on uninterrupted passage through the Strait of Hormuz—making today’s disruptions far more than a regional issue, but a direct challenge to energy security across the entire region.
What is clear now, even in the wake of a fragile ceasefire, is that the energy market is not snapping back to normal anytime soon. More than 800 vessels are currently idled in and around the Persian Gulf—ships that should be moving crude, LNG, and refined products to global buyers. That traffic jam isn’t just a headline; it’s a structural shock that could reverberate through supply chains and pricing for months to come—and quite possibly for years.
In conversations with clients, a single question keeps coming up: How do we protect ourselves from this kind of shock next time? The most effective answer is straightforward—hedging. By strategically hedging your physical and financial exposure, you can soften the impact of sudden dislocations and price spikes. Looking back, locking in prices for crude, LNG, and coal ahead of this crisis wouldn’t just have avoided pain; it would have generated significant upside and provided a powerful buffer against today’s volatility.
At Green Tiger Markets, our sole focus is helping you turn uncertainty into opportunity through effective hedging. We’re seeing unprecedented momentum on the platform—activity is climbing, matched volumes are hitting new records, and orders are being executed more quickly, in larger sizes, and across longer tenors than ever before.
If you’re looking to strengthen your risk management strategy in this environment, we’d welcome a conversation about how we can support your hedging objectives.
Interested in learning more about how to improve supply/demand balance forecasting?
Areas of Focus for Hedging
Forward prices have rallied significantly creating opportunities for generators
Significant volumes are turning over in Visayas for 1 and 2 year strips
1 year baseload strips starting over the next few months have been in the high 4s
Strong desire to sell Midday hours
May 1 year: 4750 Bid
Cal 27 4300 Bid @ 4700 Offered
We’re seeing a strong, sustained surge in engagement from a diverse mix of market participants who are actively using today’s forward levels to lock in value before the next leg of the move. Q1 set a new all-time record for matched volumes on GTM—and Q2 is already outpacing that momentum, with even higher activity levels right out of the gate.
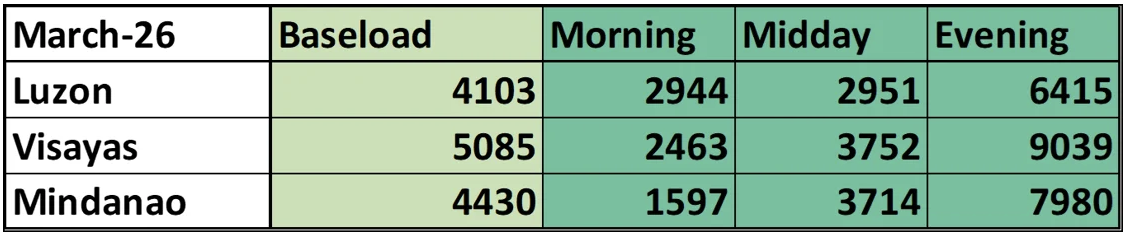
Live pricing levels:
With markets moving fast and windows of opportunity opening and closing by the day, the best way to understand what’s truly actionable is to talk with us in real time. Reach out for a live, up-to-the-minute view of active orders and curated opportunities so you can set the pace in the market—instead of reacting to it.
Meet with a GTM Risk Management Specialist
In a quick phone call we can help stabilize your future.
Market Data and Commentary
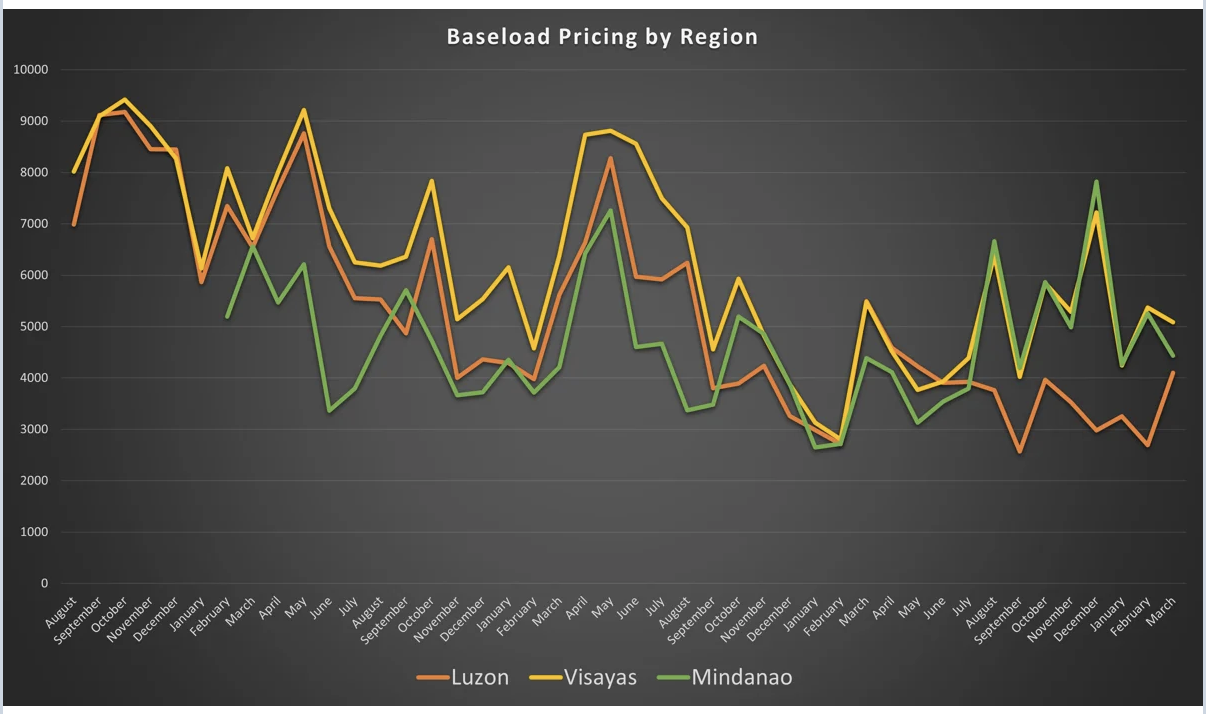
#1 Baseload Prices by Region
Luzon spot prices rebounded in March, as outages and seasonally higher demand resulted in higher pricing. In contrast, Visayas and Mindanao saw supply/demand conditions improving month on month which resulted in lower prices.
Final Luzon prices came in at 4.1 php/kwh, a good bit above the January and February prices.
Prices in Visayas and Mindanao were modestly higher than Luzon for this billing period though not as dramatic as the December pricing window. We will be keeping a watch on VisMin to see if it converges to Luzon again soon.
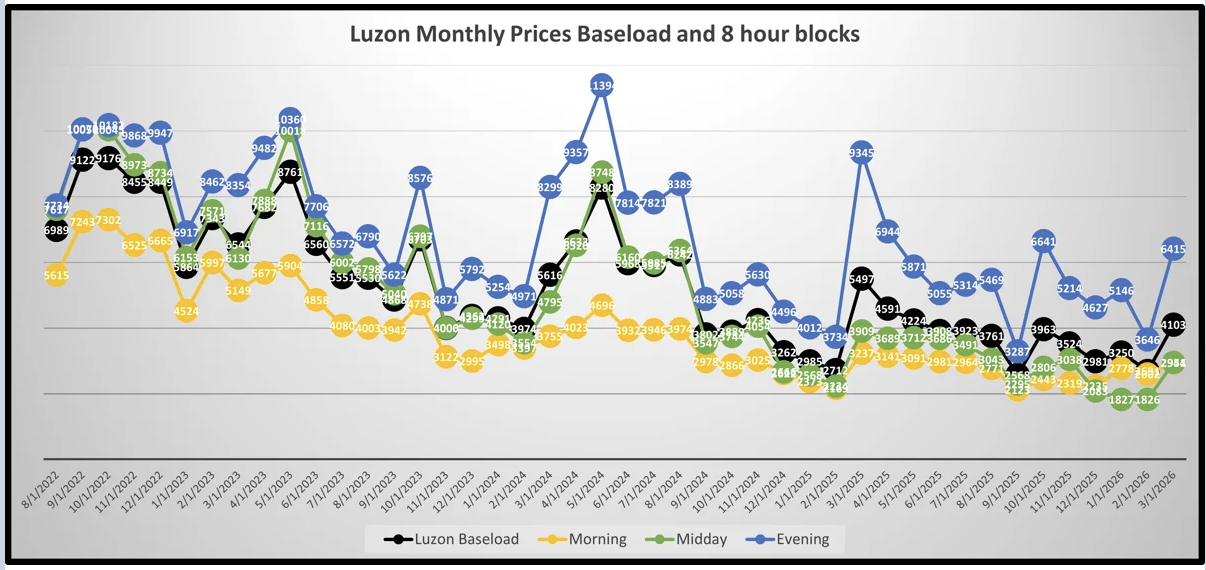
#2 Luzon prices by 8hr time block
In our second graph below, we have plotted the 8 hour time block contracts as well as Baseload.
Midday Hours continue to dislocate lower at times, with a steady repricing trend that is pushing Midday levels to match—or even trade below—Morning Hours. This is happening just as a wave of new solar capacity is coming online, providing much-needed relief in the face of disruptions across other fuel sources. In parallel, a meaningful amount of battery capacity is slated to enter the market over the remainder of the year. Together, these developments may temporarily ease the “duck curve” effect as more supply is shifted intelligently from trough to peak hours.
#3 Luzon monthly ratios by product
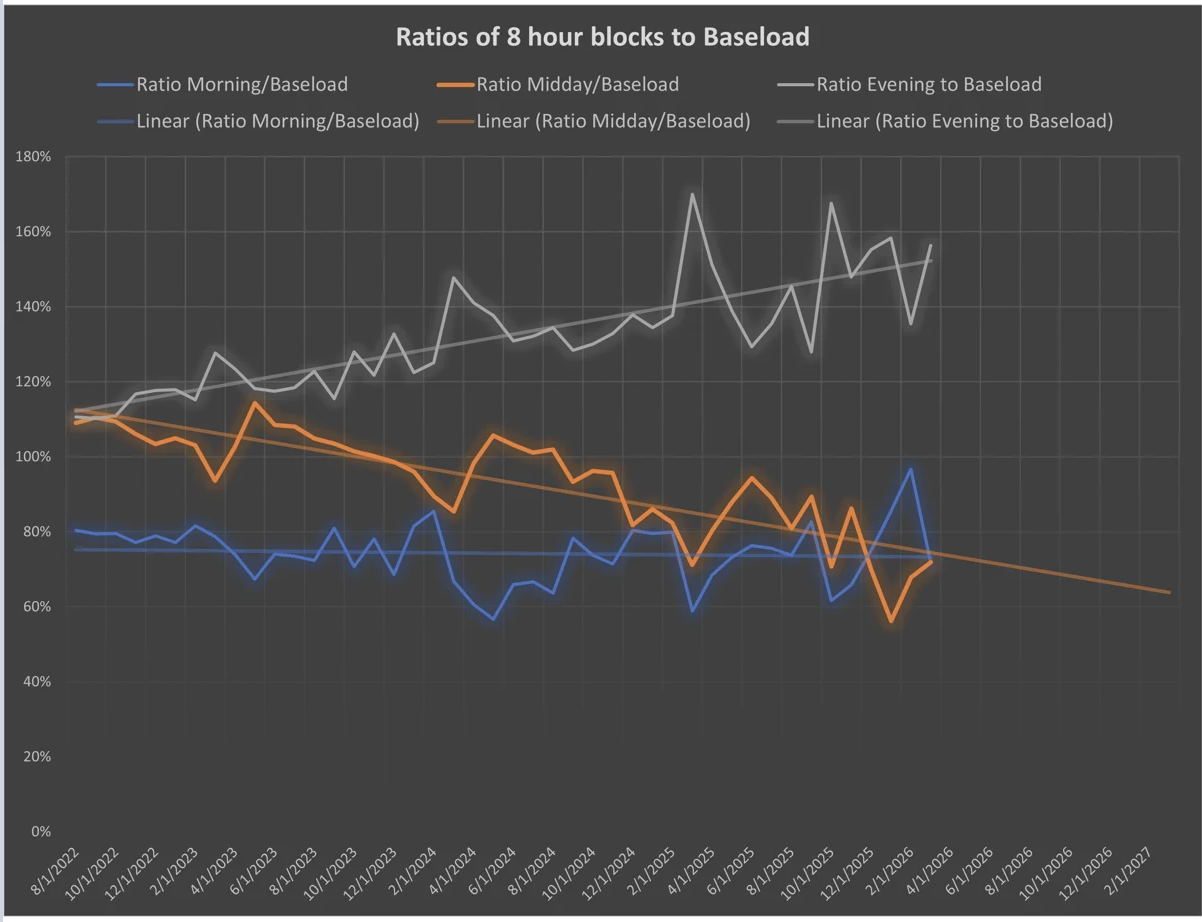
In our third graph below, we have plotted the ratios of the individual 8 hour products to Baseload.
The Evening Hours continued on their upward trend and strengthened in March relative to baseload. Midday and Morning Hours continue to be weak relative to baseload. We saw Evening Hours prices clear roughly 40% over baseload for February. Morning hours are running roughly 25% below baseload with Midday clearing at similar levels. Low overall prices made for fewer upside opportunities in spot pricing.
#4 Luzon and Visayas Baseload by year
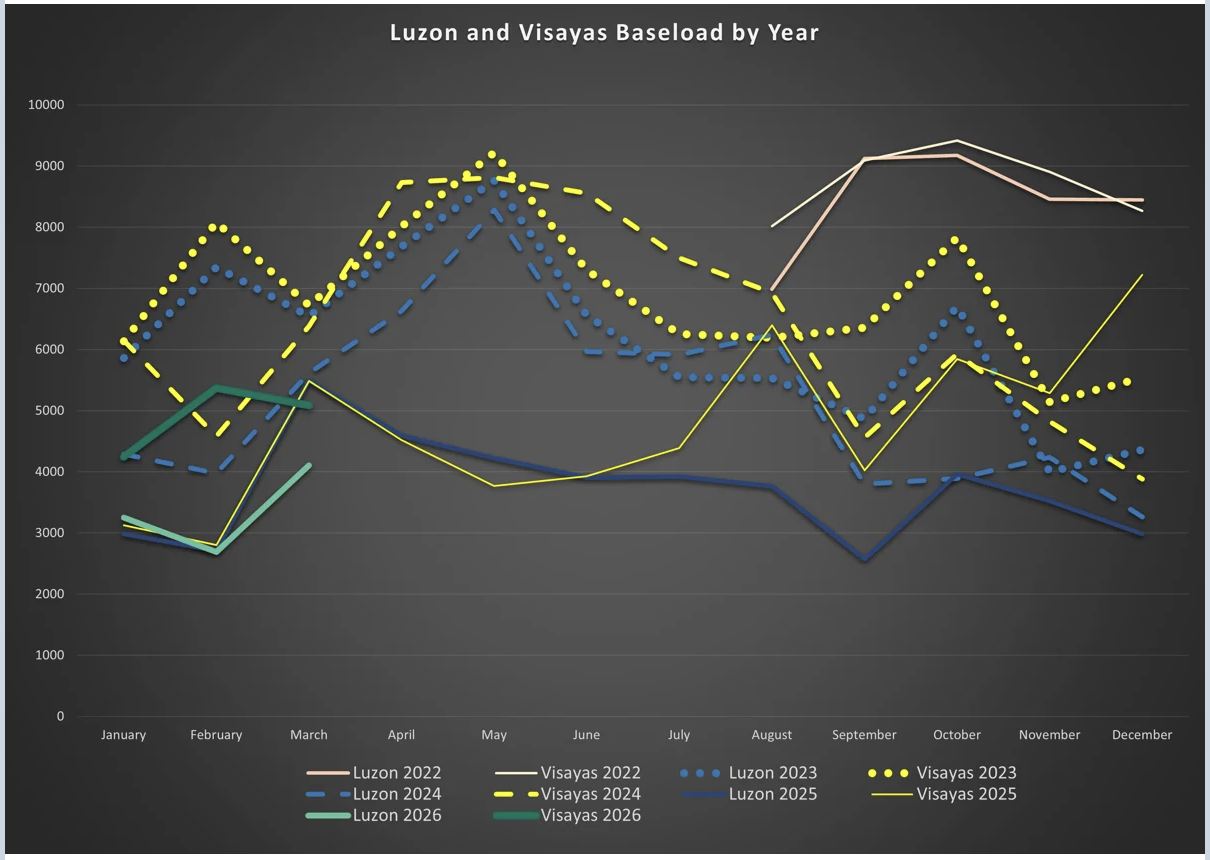
It’s anyone's guess where this year will end up. Some supply has been disrupted while a decent amount of solar supply in Luzon has been added. Demand will likely be curtailed through year end given the liquid fuels disruption. The key question is: By how much?
#5 Hourly Prices by Region
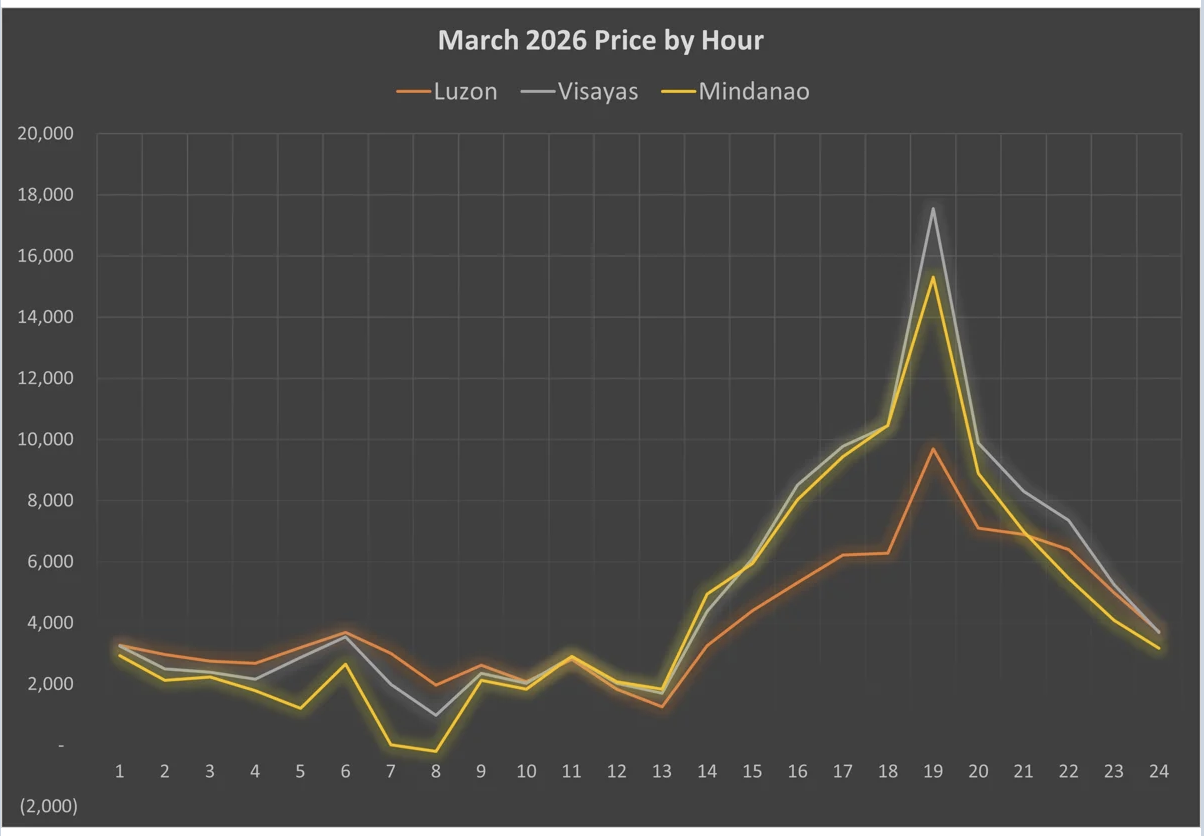
Below we have plotted hourly prices by region. Note the massive gap that opened up during Midday and Evening hours in Visayas and Mindanao vs Luzon for the past month. As more solar comes in, we expect to see more subdued midday pricing, but it could take some time. Solar penetration in Mindanao is demonstrably lower, as a percentage of the stack, compared to Luzon, so we would expect midday prices to stay strong down South.
If you are interested in learning more about our data analysis, please don't hesitate to contact us at [email protected].
New Market Participants!
We continue to add market participants and expand the number of approved counterparties for the GTM market.
As a reminder, all market participants must have net assets in excess of SGD$10mm to become approved market participants.
Market News
As per our usual practice, we have incorporated a selection of recent news stories and emerging trends in the PH electricity market. If there are any noteworthy events you would like us to share, kindly inform us! Enjoy!
Always be Hedging:
Please see our latest piece in Power Philippines. TL,DR; Hedging would have subdued this energy shock.
Asia‑Pacific's Energy Flows And Gaps In 10 Charts:
Asia-Pacific's exposure to the energy crisis is uneven, driven by import dependence, fuel mix, and limited diversification.
The Iran War’s Energy Aftershocks in the Philippines:
In an emerging market like the Philippines, where most people live with little economic cushion, a sharp increase in energy prices can have serious effects.
PH boosts diesel buffer with 52M liters Malaysia shipment:
The Department of Energy (DOE) said a second government-secured diesel shipment has arrived in the Philippines, adding 52.311 million liters to domestic supply buffers as authorities move to shield the market from ongoing geopolitical volatility.
Maharlika recalibrates toward fuel storage, grid, energy security assets amidst oil shocks:
Consing said recent developments exposed gaps in the Philippines’ preparedness for supply shocks, prompting a reassessment of priorities within the sovereign wealth fund.
ASEAN energy crisis drives coal return—but solar seen cheaper:
Zero Carbon Analytics (ZCA) indicates the shift may raise costs and weaken long-term energy security compared with renewables.
ERC imposes PHP 6,000/MWh fixed coal price under modified WESM pricing:
ERC has implemented a modified administered pricing framework for the Wholesale Electricity Spot Market
First Gen targets Q4 2026 finish for Aya hydro storage facility:
First Gen Corporation is on track to complete its 120-megawatt Aya pumped-storage project in Nueva Ecija
Coal price outlook:
Newcastle coal futures are around $135/ton and looking to head higher.
Joining the GTM Marketplace is free.
We highly encourage you to connect with other potential participants who haven't yet joined this thriving marketplace. It's an incredibly efficient way to enhance the liquidity on Green Tiger Markets. If there's a specific company you believe would be a valuable addition to our marketplace, introducing them warmly can truly make a significant impact.
Stay safe and thank you for your business!
-John Knorring, CEO Green Tiger Markets
The views contained in this newsletter are my own opinion and should not be considered investment advice or relied upon to make investment decisions. Disclaimer.
