
Green Tiger Markets: 2025 Electricity Market Review
Dear Green Tiger Market Client,
First, a big thanks to our loyal client base. Liquidity is building! Our order books have improved dramatically over the last 12 months and none of this would be happening without you.
The Philippine power market had quite a year in 2025. We thought it would be interesting for our first update of 2026 to look back on the year.
2025 was a solid year for GTM. We took over 10mm MWh of orders split almost equally between bids and offers. Baseload was the most popular product with 12 month strips of Baseload becoming a popular item.
Prior to the beginning of 2025, we had strong buyside interest with many bids coming into the market at 5500 or better. 2025 was a year with significantly lower wholesale electricity prices compared to 2023 and 2024, reflecting both robust supply and softer demand conditions across the country.
The loosening of the balances resulted in Baseload prices averaging 3.72 PHP/kWh for the year—well below 5.20 PHP/kWh in 2024 and 6.15 PHP/kWh in 2023—marking the lowest annual average since before the recent energy price shocks. Midday prices averaged about 82% of Baseload, a sign of growing renewable generation during daylight hours.
Several key drivers shaped this shift on the supply side:
Lower global coal and LNG prices reduced input costs for thermal generators.
La Niña weather patterns improved hydroelectric output, adding to overall generation capacity.
Newly installed solar capacity continued to expand, providing an increasing share of low‑cost daytime supply.
On the demand side, electricity consumption was lower in 2025 due to cooler temperatures, slower industrial production, and subdued commercial activity. The continued rollout of behind‑the‑meter solar installations—particularly among commercial customers—also displaced demand from the grid, further contributing to the moderation in spot prices. Because prices are set by the marginal electron, and there were very few hours where diesel was required, soggy pricing was the general theme.
While these softer balances have resulted in welcome relief for consumers, they have also highlighted the growing price volatility and planning challenges inherent in a more weather‑driven, renewable‑heavy system. To navigate this evolving landscape, both producers and large consumers are increasingly looking to hedging mechanisms and forward markets as tools to manage exposure and lock in cost certainty.
By expanding access to transparent hedging instruments, the Philippine market can move toward a more predictable and stable future—one where producers secure fair value for generation, consumers gain protection from price swings, and all Filipinos benefit from a more resilient energy system.
Interested in learning more about how to improve supply/demand balance forecasting?
Areas of Focus for Hedging
Forward prices have been drifting a little lower
Recent strength in WESM has provided supportive bids
Cal 26 currently valued 10% higher than where 2025 cleared
Strong desire to sell Midday hours
The forwards have stabilized despite the large selloff in September spot.
Cal 26 4000 Bid @ 4100 Offered
April for 2 years 3800 Bid @ 4300 Offered
Cal 27 4200 Bid @ 4700 Offered
Long term Baseload (5 years or more) 4200 value.
We continue to witness a strong increase in activity from a variety of participants looking to lock in prices for next year. We have registered a handful of new clients in the last two months, and they are becoming more active.
Live pricing levels
Given the fast-paced shifts in market pricing, we encourage you to reach out directly for the latest and most detailed list of active orders. Connect with us to stay ahead and access the most current opportunities—thank you!
Meet with a GTM Risk Management Specialist
In a quick phone call we can help stabilize your future.
Market Data and Commentary
#1 Baseload Prices by Region
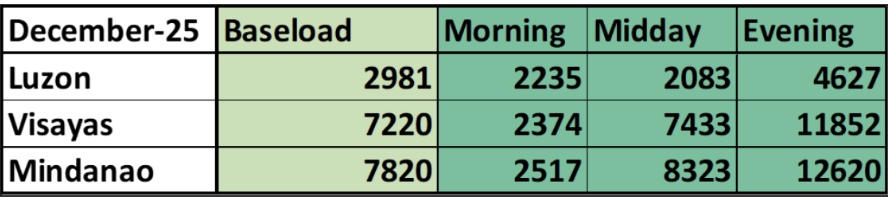
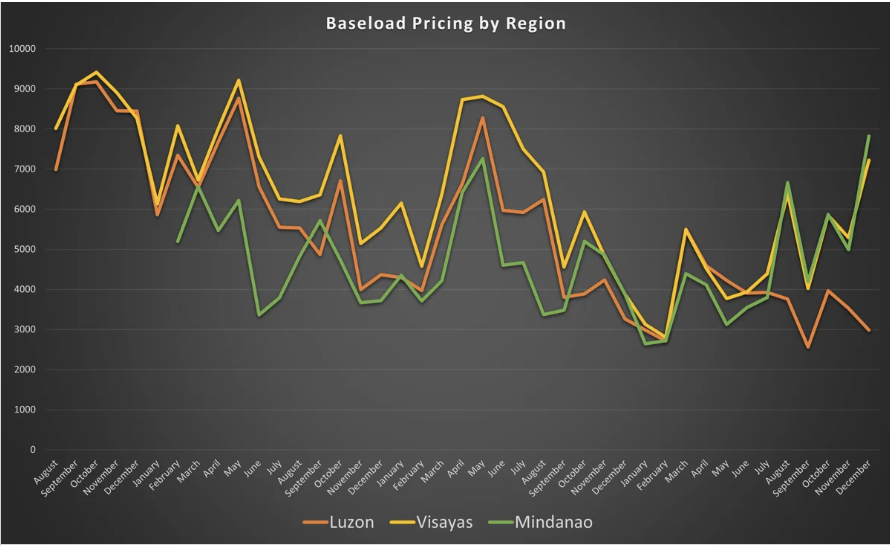
December saw seasonal moderation in Luzon spot prices with prices coming in a hair under 3php/kwh, slightly below 2024's clearing price of 3.26php/kwh. The weakness resulted in 2025 Luzon Baseload clearing 3.72php/kwh for the year. Visayas and Mindanao, however, were a very different story to close out the year and took a very bullish price path as their respective evening hours went ballistic.
As we step into the new year, prices have stabilized and appear to be trending back to the robust levels of 2024 in Luzon on the back of strong evening hour performance to start the year. Our early look has January Luzon Baseload coming in around 4.5 php/kwh well above last year's levels. Visayas and Mindanao are in the low to mid 3s php/wkh. We are still on negative price watch as load is still low but RE continues to go up.
#2 Luzon prices by 8hr time block
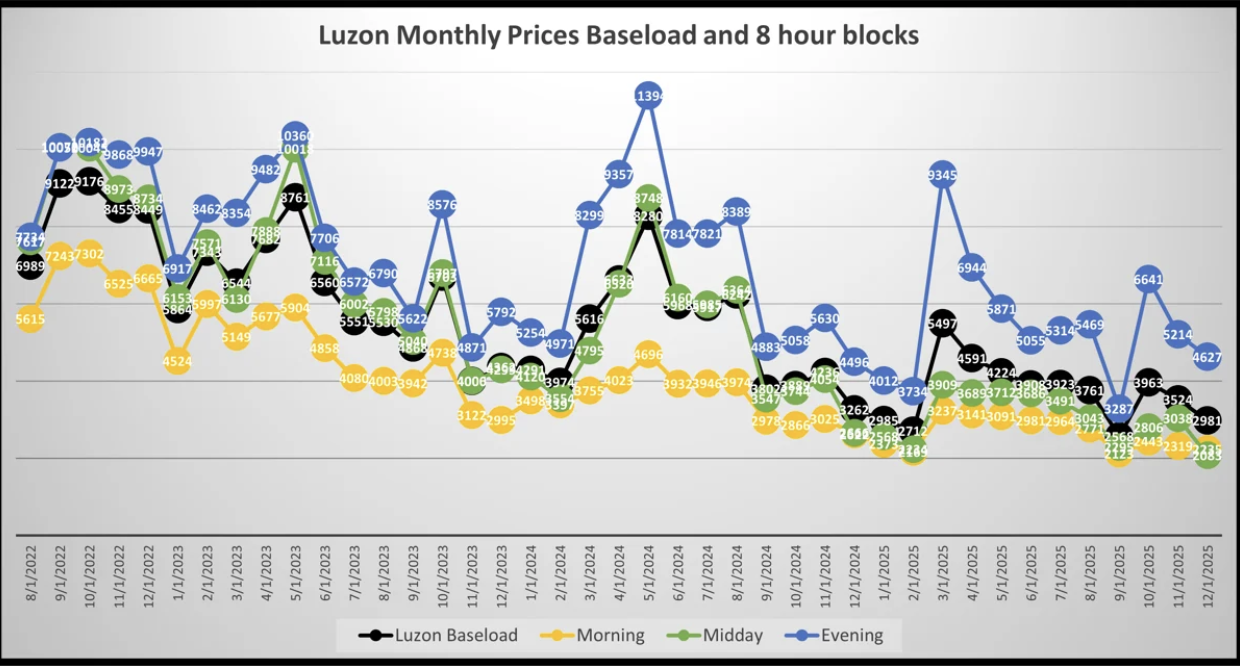
In our second graph below, we have plotted the 8 hour time block contracts as well as Baseload.
Midday Hours continue dislocating lower on occasion, with steady repricing for the Midday Hours to match Morning Hours.
Evening hours could see upward pressure as demand starts to increase, and hydro output declines.
Midday, however, continues to average well under Baseload in Luzon. We expect Midday to continue deteriorate given lower seasonal loads and new solar facilities continue to get energized.
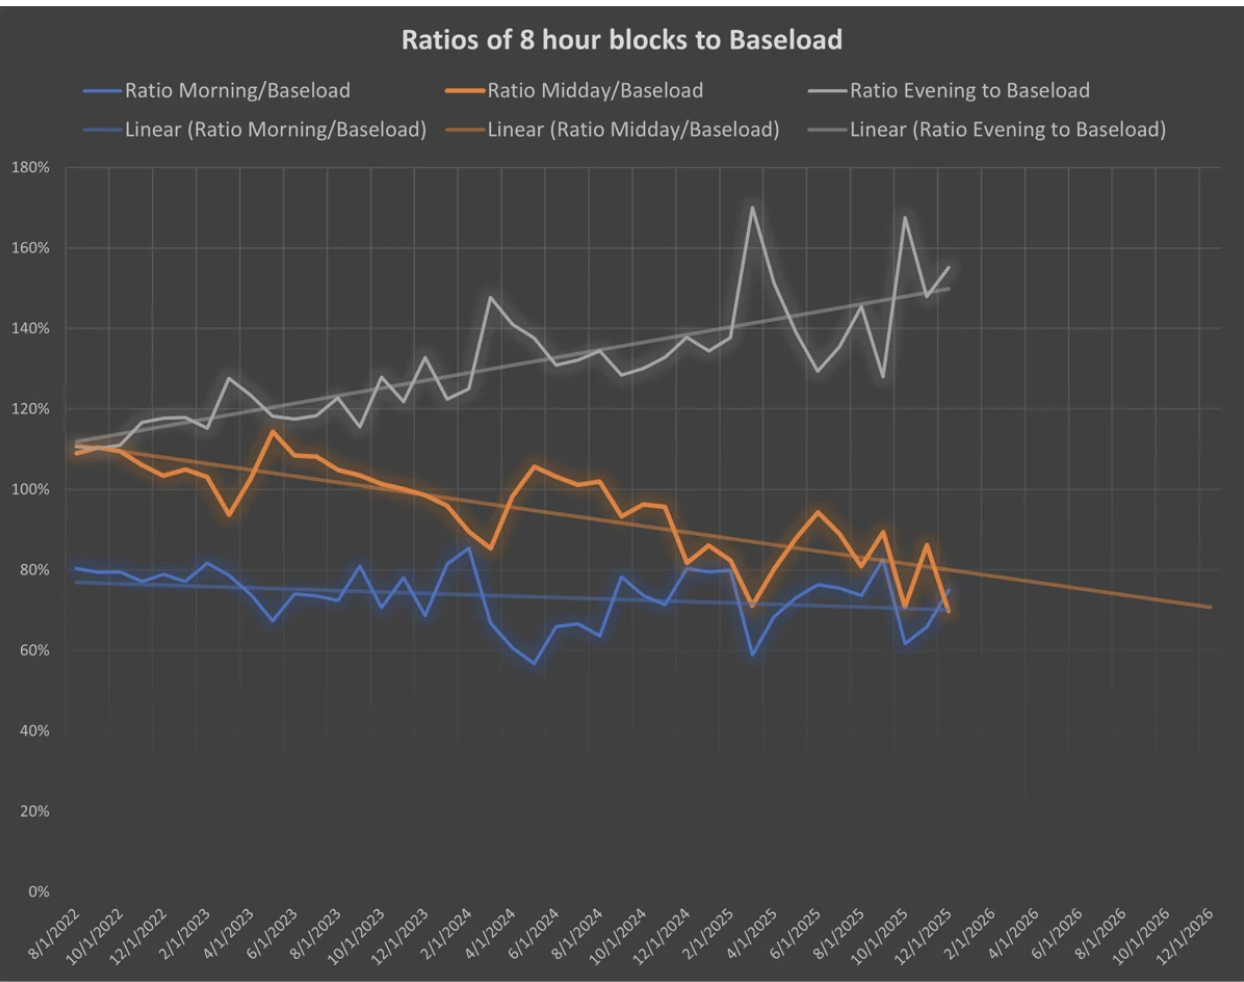
#3 Luzon monthly ratios by product
In our third graph below, we have plotted the ratios of the individual 8 hour products to Baseload. The Evening Hours rallied in December, likely driven by a seasonal rise in outages and lower hydro output. Midday and Morning Hours continue to be weak relative to baseload. We saw Evening Hours prices clear roughly 55% over baseload for December. Midday and Morning are running roughly 30% below baseload with Midday leading the way lower.
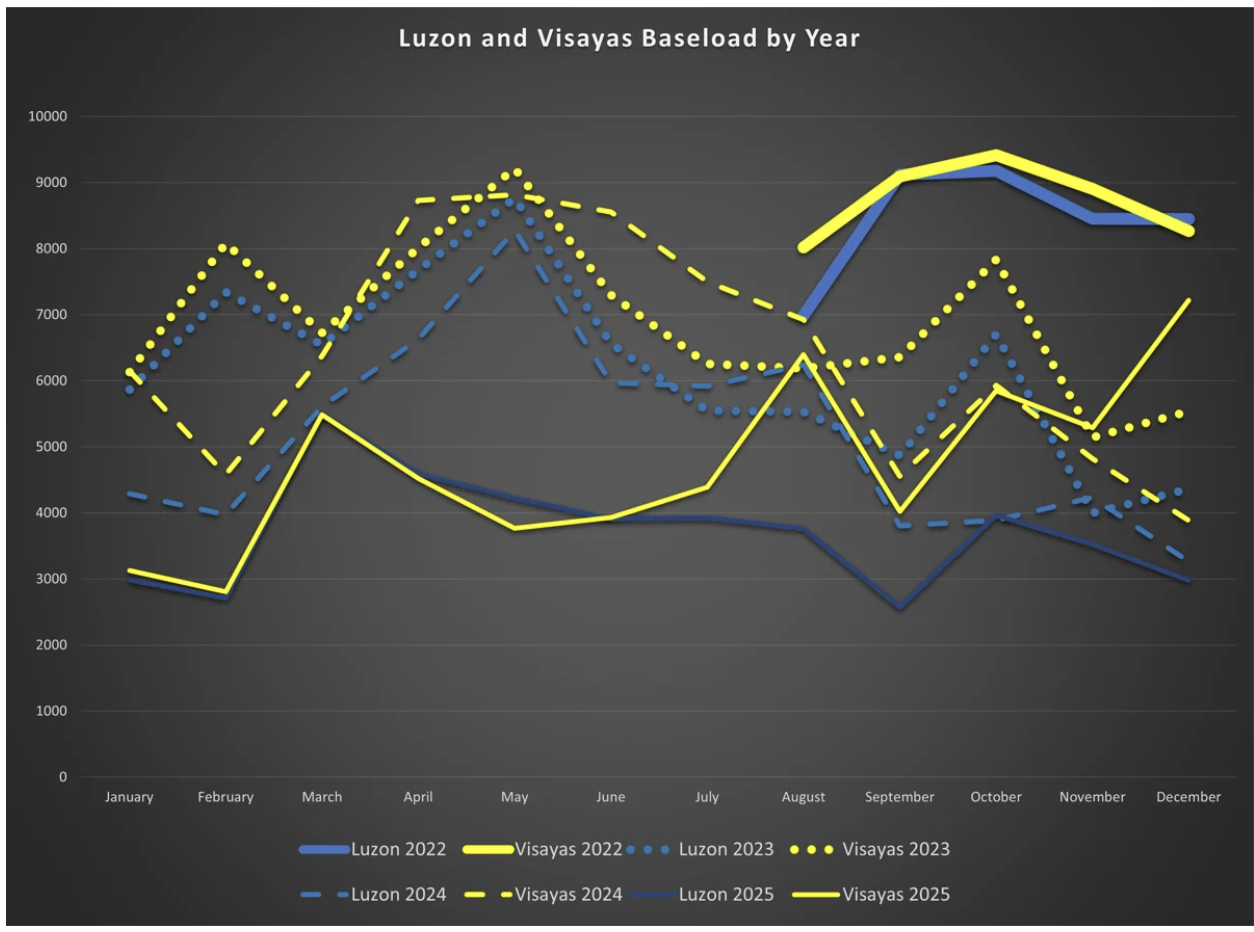
#4 Luzon and Visayas Baseload by year
For Luzon, 2025 was bearish when compared to the last few years. Every month in 2025, with the exception of October, has cleared below 2024. We saw some weakness in Luzon to close out 2025, so it is worth keeping an eye out for further weakness. Visayas, on the other hand, after spending most of the year well below 2024 prices, put in a more constructive finish to the year.
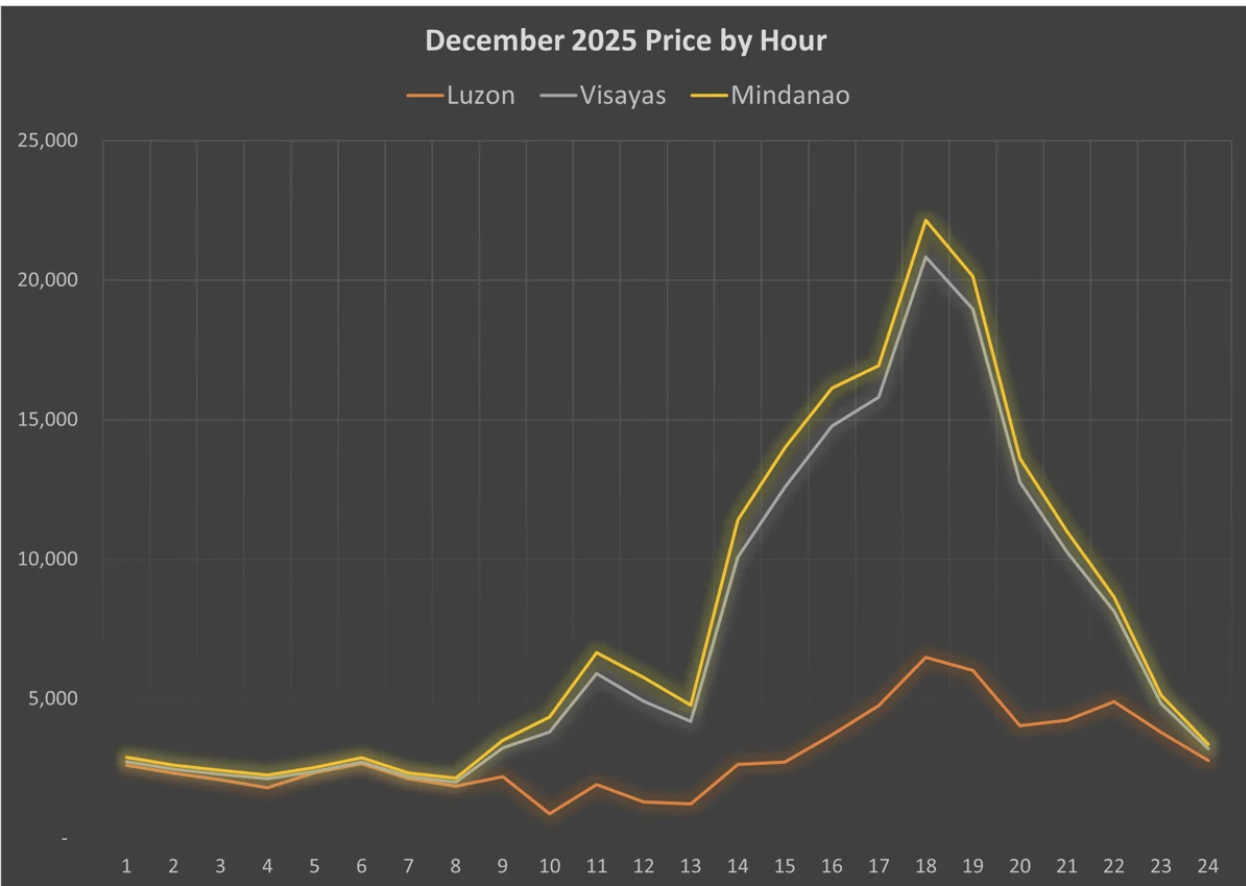
#5 Hourly Prices by Region
Below we have plotted hourly prices by region. Note the massive gap that opened up during Midday hours in Visayas and Mindanao vs Luzon. As more solar comes in, we expect to see more subdued midday pricing, but it could take some time. Solar penetration in Mindanao is demonstrably lower, as a percentage of the stack, compared to Luzon, so we would expect midday prices to stay strong.
If you are interested in learning more about our data analysis, please don't hesitate to contact us at [email protected].
New Market Participants!
We continue to add market participants and expand the number of approved counterparties for the GTM market.
As a reminder, all market participants must have net assets in excess of SGD$10mm to become approved market participants.
Market News
As per our usual practice, we have incorporated a selection of recent news stories and emerging trends in the PH electricity market. If there are any noteworthy events you would like us to share, kindly inform us! Enjoy!
Why the Philippines needs forward electricity markets:
Without a way to manage price risk in an increasingly volatile power market, many renewable projects may never reach financial close.
DOE seeks PHP 24 billion from Solar Philippines:
Penalties cover performance bonds, contractual obligations, and other required payments, that developers are required to settle when projects fail to move forward as committed.
EDC eyes PHP 100 billion upgrade to expand Tongonan geothermal complex:
PHP 100 billion to expand and upgrade its Tongonan Geothermal Project in Leyte
BDO to provide PHP 50bn to finance gas assets:
The financing package that supported Prime Infra’s acquisition of First Gen Corporation’s gas assets.
Power suppliers offer over 700 MW for Meralco’s 200-MW baseload requirement:
Meralco said a total of 15 generation companies expressed intent to participate in its Competitive Selection Process (CSP).
DOE frees up 18 GW of stalled RE projects:
(DOE) has terminated or accepted the surrender of 17,904 MW worth of RE projects in 2024 and 2025, as part of a government-wide effort to remove delayed and non-performing developments from the pipeline.
Vivant Energy bags 15-year deal to supply Siquijor with 11 MW:
Siquijor’s power constraints have drawn national attention. The province was placed under a state of calamity in June 2025 after outages stretched to as long as 20 hours a day.
ERC defends GEA-All approval amid consumer cost concerns:
The GEA-All allows the recovery of costs needed to support renewable energy developers that win government-run green energy auctions.
Coal price outlook:
Newcastle coal futures are around $105/ton and looking to head lower.
Joining the GTM Marketplace is free.
We highly encourage you to connect with other potential participants who haven't yet joined this thriving marketplace. It's an incredibly efficient way to enhance the liquidity on Green Tiger Markets. If there's a specific company you believe would be a valuable addition to our marketplace, introducing them warmly can truly make a significant impact.
Stay safe and thank you for your business!
-John Knorring, CEO Green Tiger Markets
The views contained in this newsletter are my own opinion and should not be considered investment advice or relied upon to make investment decisions. Disclaimer.
