
Green Tiger Markets PH Electricity June Update
Dear Green Tiger Market Client,
Now that we have the first five billing months of 2025 in the rearview mirror, the GTM Team thought it would be helpful to investigate where power prices have shaken out so far and what the future may bring. Understanding why prices are clearing where they are is just as important, so we will also be taking a look at some of the driving factors.
Through May, Luzon Baseload has averaged almost exactly 4PHP/KWH. Last year, the first 5 months averaged approximately 5.75, a dramatic change from last year. By day segment, the Mornings (-28%) and the Midday (-42%) prices have seen the most downside pressure while Evenings are only 24% lower. These movements in realized spot prices are rather dramatic and a welcome surprise for the average Filipino consumer.
Downside pressure in prices is coming from multiple factors which are all conspiring to make supply/demand balances looser year on year. Some of the key factors driving the decline in prices include:
Substantially cheaper coal prices, including a 30% decline in Newcastle prices
Increased supply from both Natural Gas and Solar generation
Cooler temperatures with the passing of El Nino
Greater grid connectivity and transmission upgrades
Looking to the future, where might prices end up? The final 7 months of 2024 averaged 4.75. While we do expect that prices will continue to be soft, as more generation gets connected through year end, we don't expect prices to average 30% under last year. Our forecast is closer to 20% under last year, leaving an average of 3.9 for 2025.
Interested in learning more about how to improve supply/demand balance forecasting?
Areas of Focus for Hedging
Continued buyside interest from RES to lock in margins
Continued interest in outright months and strips in 2025
Sellers are sniffing around in 2026, and now 2027
We are working several orders for 2025 Luzon baseload power. Midday hours are generally being offered at 15-25% below baseload prices while bids have been scarce. Evening hours are generally being bid at 140-160% of Baseload, with offers being scarce. Here are some of the most intriguing opportunities, all values in quoted in PHP/Mwh:
September-December Baseload: 4500@4800
July-November: 5200 bid
July-December: 5200 offered
Cal 26 5000@5300
We're witnessing a increase in activity from a variety of participants looking to lock in prices for the balance of the year. In general, the bids that we are seeing are quite strong, often well in excess of last year's prices
Live pricing levels
As prices continue to fluctuate with the changing market dynamics, we kindly request that you contact us directly for the most up-to-date and comprehensive list of orders we are currently handling. Thank you!
Meet with a GTM Risk Management Specialist
In a quick phone call we can help stabilize your future.
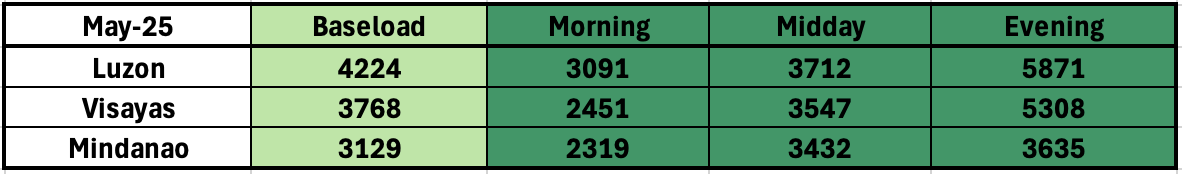
Since our last update, the Philippines electricity market has continued to experience notable shifts in WESM pricing, reflecting both market dynamics and structural advancements. In May 2025, WESM recorded a price decline, month on month, of about 10%, dropping to PHP 4224/MWh from PHP 4591/MWh in April. The price decline was driven by increased supply availability combined with modest demand, leaving significant reserve margins, as reported by IEMOP.
Soggy prices are becoming a greater concern for unhedged generators. To put it in perspective, for a generic 300Mw power plant, with 80% capacity factor, when prices average 5Php/Kwh, revenues are around 10.5bn. A 1Php/kwh move lower causes a drop in revenue of just over 2bn. Several generators benefited in years past from being unhedged, but this year is quite a shift for them.
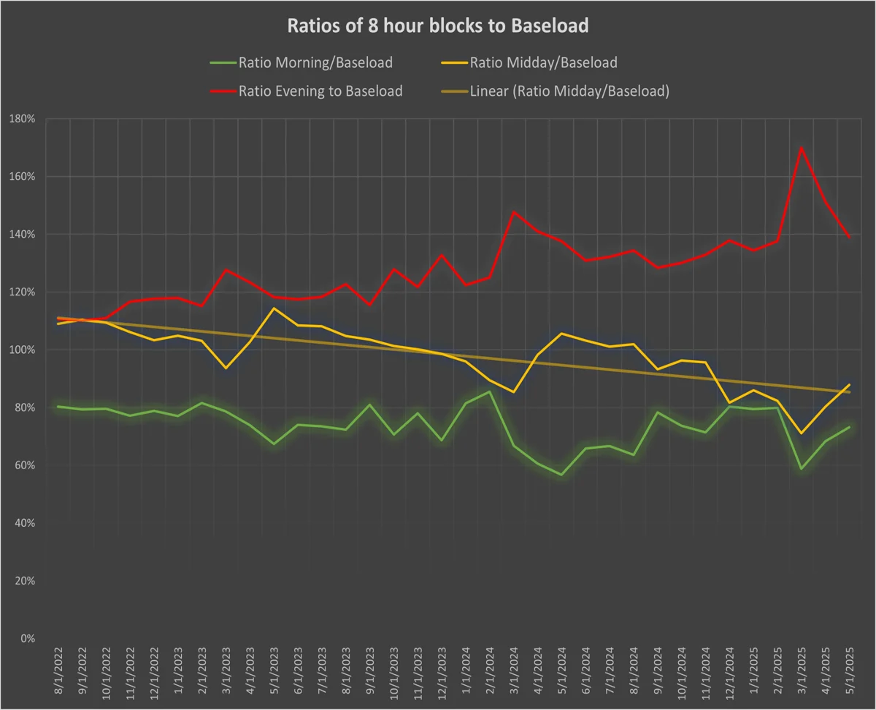
Midday prices continue to feel downward pressure, though not as significant as last month. While we didnt see any negative pricing hours in the Midday, prices still averaged about 12% under baseload. Our expectations are that pricing will continue to deteriorate into year end as more solar projects are tied in and energized.
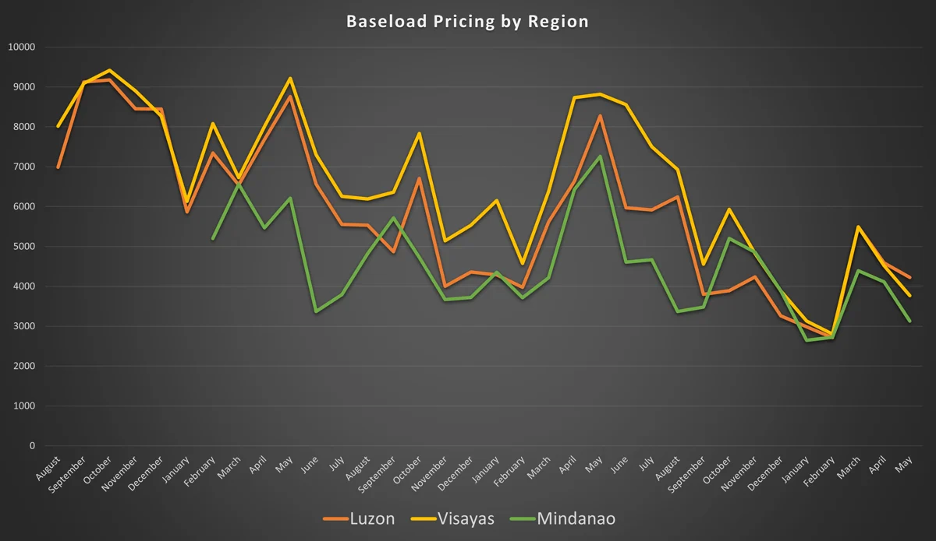
Of note, the spread between Luzon and Visayas has continued to come in with Luzon finishing May over Visayas. We were regularly seeing Visayas print 1000 or 2000 pesos over Luzon. The last few months have had them plugged right on top of one another, and now Visayas moving lower. It doesnt take much new generation at the margin to put a cap on Visayas.
As we step into June, we are in the traditional heart of the summer pricing, however this year, prices have been distinctly soft. Our early look actually has June coming in around 4250 so far, substantially weaker than where the forwards were just a few weeks ago. We had been expecting to see some stress in the grid for summer load, but those fears have yet to realize.
#1 Baseload Prices by Region
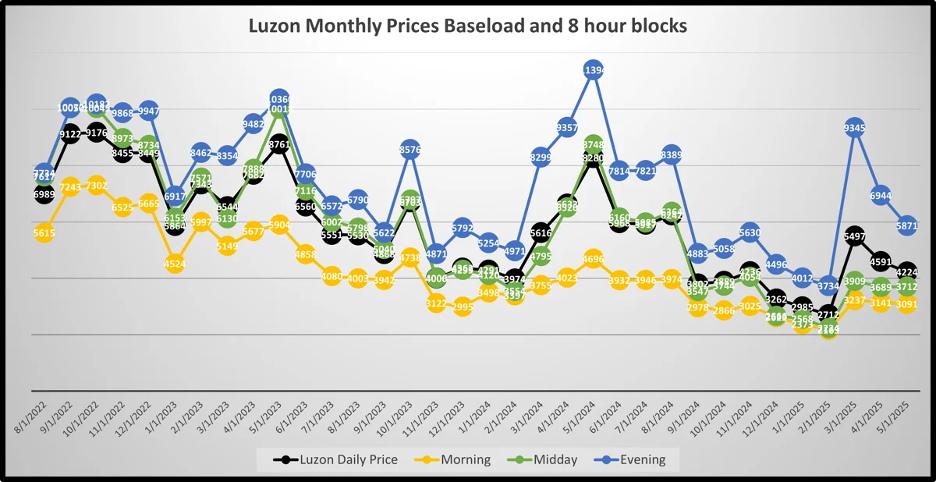
In our second graph below, we have plotted the 8 hour time block contracts as well as Baseload. Evening prices had been headed steadily lower since popping during the March outages. The downtrend resumed in May and will likely persist given the incremental solar coming to the market and the new gas fired thermal plants will have fewer premium hours to amortize their fixed costs over. There has been virtually zero need for diesel to run
Midday Hours continue dislocating lower on occasion, with steady repricing for the Midday Hours to match Morning Hours.
Evening hours could see pressure from some of the new gen that is being connected through the balance of the year, but it is a very much wait and see for the evening hours.
#2 Luzon prices by 8hr time block
In our third graph below, we have plotted the ratios of the individual 8 hour products to Baseload. The trend continues for Evening Hours to diverge and become more "peaky", though there was a slight retracement in May. The trend continues for Midday and Morning Hours to become more subdued relative to baseload. We are seeing Evening Hours prices clear roughly 40% over baseload for May and Midday running 15% below baseload. This does not bode well for unhedged solar developers, but could create a massive opportunity for battery operators as well as dispatchable hydro.
#3 Luzon monthly ratios by product
Year-on-Year comparison
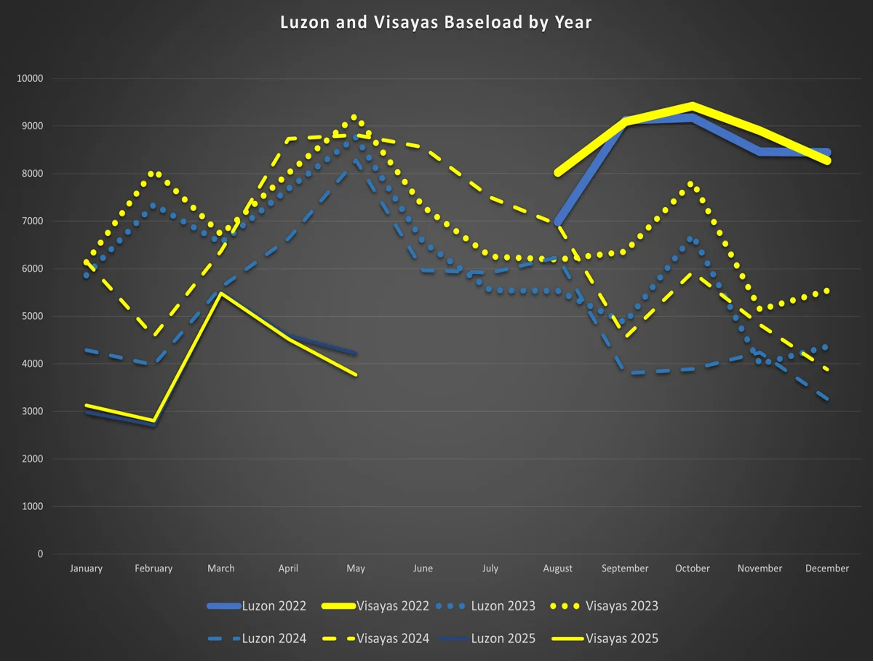
This year looks significantly different from the last few years. May resumed the weakness after the brief spike in March prices. On the year, Baseload is averaging around 4000, or a full 1750 php below last year. What does this mean for the balance of the year and into 2026??? Will 2025 average in the 3s?
#4 Luzon and Visayas Baseload by year
Hourly Pricing
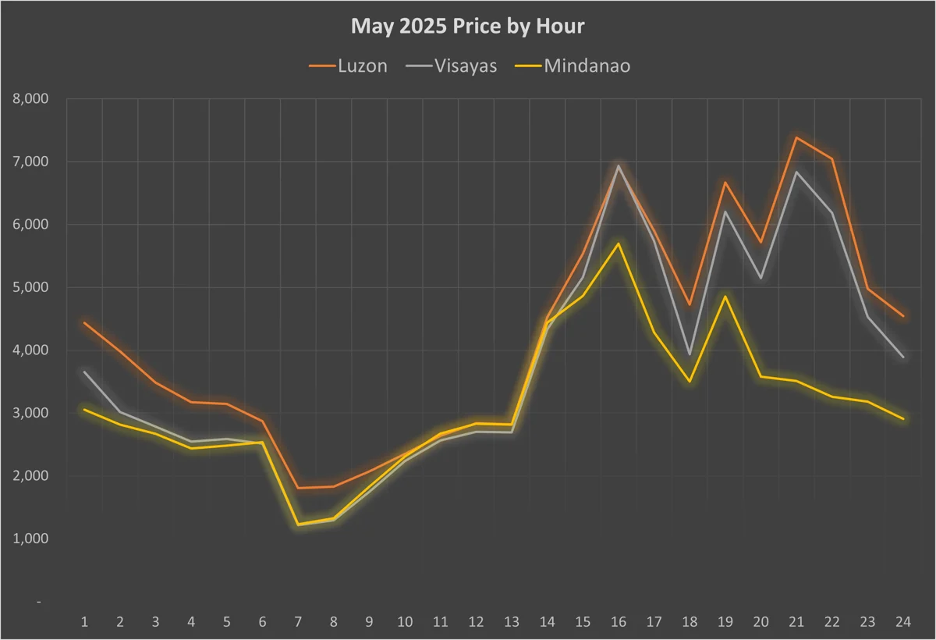
Below we have plotted hourly prices by region. Evening Hours continue to be strong relative to Midday and Morning prices. The "duck curve" is becoming more and more pronounced.
#5 Hourly Prices by Region
If you are interested in learning more about our data analysis, please don't hesitate to contact us at [email protected].
New Market Participants!
We continue to add market participants and expand the number of approved counterparties for the GTM market.
As a reminder, all market participants must have net assets in excess of SGD$10mm to become approved market participants.
Market News
As per our usual practice, we have incorporated a selection of recent news stories and emerging trends in the PH electricity market. If there are any noteworthy events you would like us to share, kindly inform us! Enjoy!
When the Sun Comes Out: How Renewables Are Reshaping Intraday Energy Prices in the Philippines:
The flood of renewables is putting downward pressure on prices.
Read more here
Coal Price Outlook
Newcastle coal futures are hovering just above $105/ton after bouncing 10% on weaker supply volumes out of Australia.
MGen eyes more LNG sources as gas plants near completion:
Manny Rubio, CEO, specified that MGen is expecting the 2,500-MW gas capacity to be available.
Prime Infra secures 2GW of pumped storage in GEA 3:
DOE recognized Prime Infra’s 600MW Wawa and 1,400MW Pakil pumped storage projects, both targeted for commercial operations by 2030.
DOE hails PhilATOM ratification as milestone for nuclear energy:
DOE has lauded the ratification of the Philippine National Nuclear Energy Safety Act
JNEC signs La Rose Noire:
JNEC RES announced it has signed an agreement with La Rose Noire, a global supplier of luxury baked goods, to supply electricity
Joining the GTM Marketplace is free.
We highly encourage you to connect with other potential participants who haven't yet joined this thriving marketplace. It's an incredibly efficient way to enhance the liquidity on Green Tiger Markets. If there's a specific company you believe would be a valuable addition to our marketplace, introducing them warmly can truly make a significant impact.
Stay safe and thank you for your business!
-John Knorring, CEO Green Tiger Markets
*The views contained in this newsletter are my own opinion and should not be considered investment advice or relied upon to make investment decisions. Disclaimer.
